

After experiencing initial selling pressure, global stocks and bonds have temporarily stabilized, with market attention focused on the upcoming release of the United States' PCE inflation data.
On Wednesday, the MSCI Asia-Pacific index rose by 0.9%, poised to record the largest single-day increase in three weeks. U.S. stock futures rose, with the Dow Jones futures increasing by 0.5%, and European stocks opened higher. The yield on 10-year U.S. Treasury bonds declined, Brent crude oil fell by 1%, and spot gold rose by 0.44% during the day, reaching above $4,200.
Oil prices and the US-Iran situation remain the main uncertainties in the market. Rising energy costs could push up inflation and strengthen market expectations for further interest rate hikes by the Federal Reserve, driving global bond yields to multi-year highs. At the same time, corporate earnings reports next month will be crucial for the market to assess whether the high valuations of US stocks are supported by actual profits.
Arjun Vij, a fund manager at JPMorgan Asset Management, stated: "The selling of bonds may stop for one of the following reasons: a rapid resolution to the Middle East conflict, a significant decline in U.S. stocks driven by slower hard economic data, or a decrease in profits and slower performance forecasts."
The core market trends are as follows:
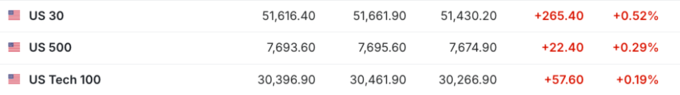
- S&P 500 index futures rose by 0.3%, Nasdaq 100 index futures rose by 0.2%
- The European Stoxx 50 index opened up 0.23%, Germany's DAX index rose 0.43%, the UK FTSE 100 index increased by 0.39%, and France's CAC 40 index gained 0.04%.
- The Nikkei 225 index closed up 1.9% at 66,753.72 points; the Tokyo Stock Exchange index in Japan closed up 1.7% at 4,108.65 points; the South Korean KOSPI index closed down 0.48% at 6,838.04 points.
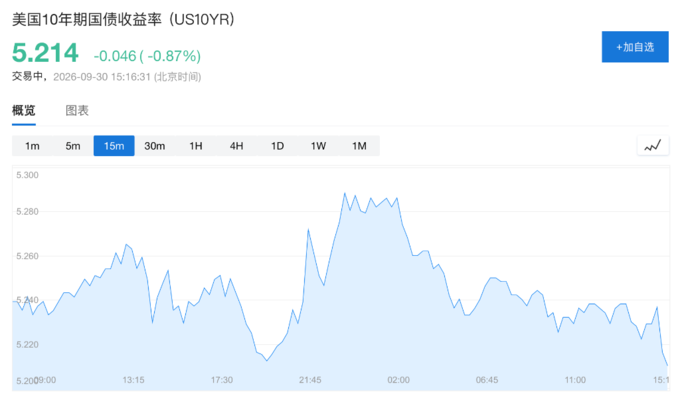
- The yield on 10-year U.S. Treasury bonds fell slightly to 5.21%.
- Brent crude oil tumbled 1.0% on the day to close at $95.18 per barrel
- Spot gold reached $4,200 per ounce, up 0.44% for the day.
U.S. stock index futures rose, with the Dow Jones futures up 0.5%, the S&P 500 index futures up 0.3%, and the Nasdaq 100 index futures up 0.2%.
Market attention has shifted to the U.S. personal consumption expenditure ( PCE ) data for August, which will be released on Wednesday. As the Federal Reserve's preferred inflation indicator, markets expect both the overall and core PCE year-on-year growth rates to accelerate in August.
KCM Trade Chief Market Analyst Tim Walters stated that if the data exceeds expectations, it may strengthen the Fed's hawkish stance and provide a basis for further policy tightening; if the data is weaker, it may cause the market to re-evaluate the necessity of a rate hike in October and weaken the recent upward trend in U.S. Treasury yields.
The US Dollar Index has stabilized, showing promise to record its best single-month performance since June. As the Federal Reserve refocuses on curbing inflation, market interest rate expectations continue to rise. Yields on US Treasury bonds of various maturities have temporarily stabilized, with the 10-year Treasury yield at 5.21%.
Brent crude oil tumbled 1.0% on the day to close at $95.18 per barrel.
According to the latest research report released by JPMorgan Chase on September 29, the 10-day average of total oil exports from the Middle East has rebounded to 20.5 million barrels per day, which is 89% of the pre-war level in 2025, with only a 11% difference from that time. JPMorgan Chase' commodities research team believes that the crude oil market has largely normalized. This means that despite ongoing regional conflicts, a substantial recovery on the supply side has been confirmed by the data.
Spot gold reached $4,200 per ounce, up 0.44% for the day.