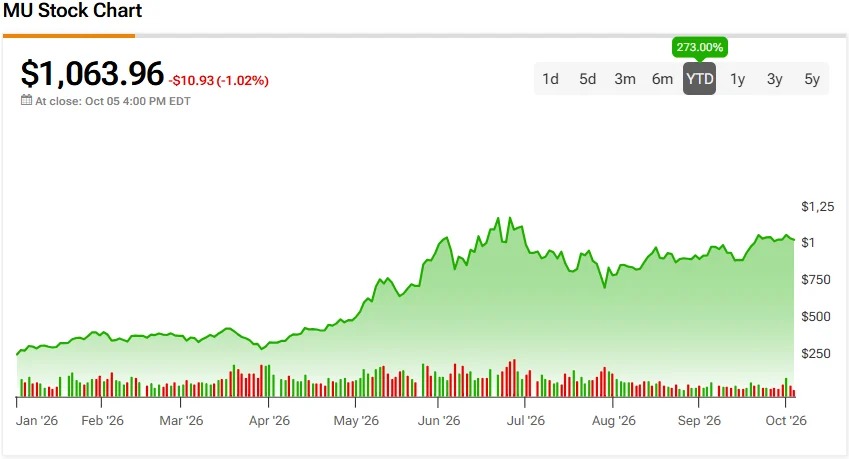


Micron Technology ( Micron , NASDAQ : MU ) seems to be showing some “post-financial-report fatigue” recently. This storage chip giant has continuously delivered impressive results, but market enthusiasm often doesn’t last too long. Following the release of its financial report in June, MU soared by about 16% on the following trading day because the results far exceeded expectations; however, five trading days later, almost all of that gain after the financial report had been lost.
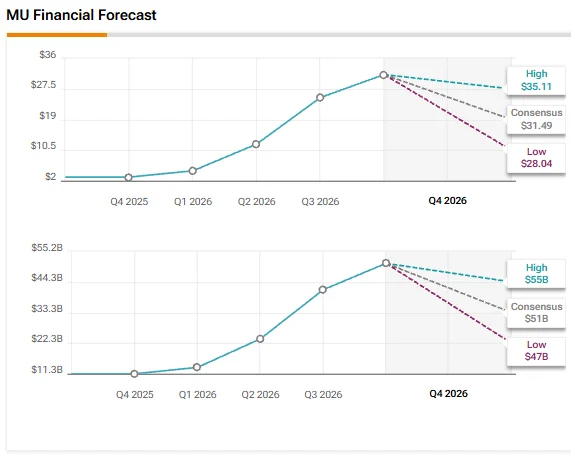
A similar situation occurred in the latest season: investors once again lost their enthusiasm shortly after strong financial results were announced. Micron reported revenue of $54.23 billion for the fourth quarter of fiscal year 2024, a year-on-year increase of 379%, exceeding Wall Street's forecast of $51.49 billion; the adjusted earnings per share were $33.42, also above market expectations. Management subsequently provided revenue guidance for the first quarter of fiscal year 2025 of $60 to $63 billion, with the mid-range also exceeding the market consensus. However, MU only rose by about 3% on Thursday, and then lost that portion of gains over the following two trading days.
One investor who believes that the hesitation following this financial report deserves serious consideration is Rational Techne ( RT ). Despite the company's outstanding financial performance, he remains very bearish. His concerns are partly focused on retail investors; although it is difficult for the stock price to continue the upward trend after another strong quarterly report, retail investors' confidence in MU still seems intact.
RT indicates that: 'In a bubble atmosphere, the behavior of retail investors, overall, is typically a counterindicator to the best actions for long-term investors.'
In his view, this kind of confidence may expose buyers to risks when expectations far exceed sustainable performance. RT does not believe that the recent improvement in profitability signifies a permanent change, but rather suggests that there are several factors that could make the future environment less favorable.
One concern is that in the coming years, more storage chip supply will enter the market. New manufacturing capacity is expected to start entering the market from 2027 and continue through 2028, and Chinese manufacturer ChangXin Memory ( CXMT ) may also become another source of global competition. RT also doubts whether long-term customer agreements can truly provide the protection that bulls expect when the industry is weakening.
These concerns brought RT back to the topic of Micron's relatively lukewarm reaction even after another explosive quarterly earnings announcement. He said, "The market believes that we are very likely at the cyclical peak for Micron."
According to this interpretation, outstanding quarterly data alone is not sufficient to support the current valuation of MU. RT believes that the current stock price already takes into account the expectation of a continuously favorable storage chip environment in the coming years; once supply expansion slows down or spending on artificial intelligence declines, the stock price will become more vulnerable. Considering that the stock has already risen by 273% as of 2026, he feels that the balance between the remaining upside potential and potential downside risks is not favorable.