After facing a cold reception from investors in the public market, Australian data center operator Firmus Grid announced the withdrawal of its plan to list on the Australian Stock Exchange and turned to seeking private financing instead. This is the second major data center company IPO to fail within three weeks, and the public market pricing of AI's infrastructure assets is now facing severe challenges.
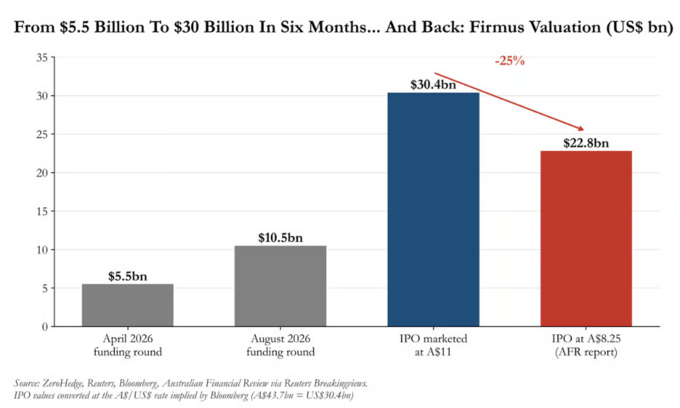
Firmus originally planned to raise up to $5.5 billion, with a pricing of A$11 per share, corresponding to a valuation of about A$43.7 billion ($30.4 billion). According to Bloomberg, as of the subscription deadline, there was no clear pricing or transaction structure in the inquiry book. Firmus once lowered the issue price to A$8, which is about 25% lower than the issuance range, and attempted to hold the bottom line at A$8.25.
Ultimately, on Friday, the company announced the withdrawal of its listing application, citing "recent market fluctuations and current market conditions" as reasons. It stated that "the trading terms do not fully reflect the company's business strength and long-term growth prospects," and indicated that it would turn to the private equity market to seek funding.
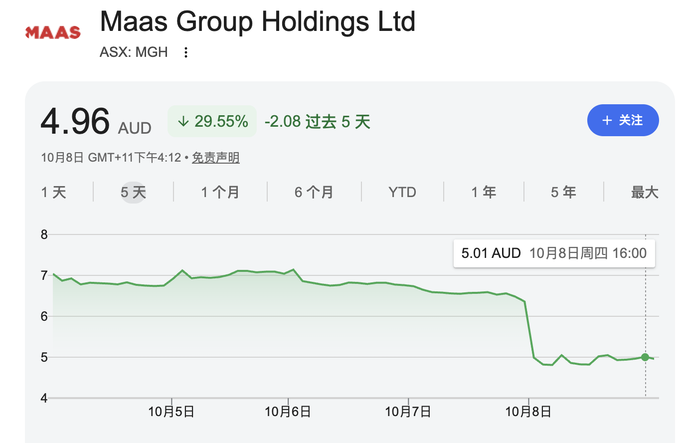
This setback has directly impacted related parties. The stock price of Maas Group, one of the shareholders of Firmus, plummeted by 30% at one point during trading, setting a new record for the largest single-day decline in history.
Six-month valuation surge sixfold: from 5.5 billion to 30.4 billion US dollars
Firmus2019 started its business with Bitcoin mining and in February of this year, it secured a $10 billion debt financing led by Blackstone and Coatue; in April, Coatue led a round of financing that valued the company at $5.5 billion; in August, a $2 billion financing involving NVIDIA, Coatue, Blackstone, and Jane Street raised the company's valuation to $10.5 billion; less than two months later, IPO requested that public market investors enter the market at a valuation three times that of the August financing price.
In contrast to this valuation, according to Breakingviews, Firmus currently has only an actual built capacity of 42 megawatts out of a total planned capacity of about 1 gigawatt, which accounts for approximately 4%. The company has recently shifted its business focus from Australia to Malaysia and Indonesia, with the aim of serving ultra-large-scale cloud computing customers such as OpenAI and Meta.
According to the draft prospectus, the company incurred a net loss of $77 million in the first half of the year on FY27, and no performance forecasts beyond June 2027 were provided.
Australian local institutional investors are unenthusiastic:
- Morningstar Analyst Lochlan Halloway directly points out that this IPO possesses characteristics of a "prosperous period" and believes that the "sharp increase" in valuation in the short term is cause for concern.
- The Kirit Hara of Merlon indicates that its investment process 'does not allow us to buy what we hope for and dream of'.
- The Romano Sala Tenna of Katana frankly stated, "We are facing difficulties in fundamental arithmetic."
- The Joseph Koh of Blackwattle refused to participate in the subscription, citing "too many unknown factors" as the reason.
Alternative valuation tools failed to convince institutions
When traditional financial indicators are insufficient to support pricing, the underwriters of Firmus turn to a new valuation framework known as “EV +1/ EBIT +2”. According to the explanation by Antony Currie of Breakingviews, this indicator calculates the enterprise value based on the company's net liabilities after 12 months, divided by the expected earnings before interest and taxes (EBIT) to be realized in two years.
The logical starting point is that data center developers typically cover up to 90% of the construction costs with debt and can begin generating revenue within about a year, therefore it is difficult for the financial figures of that period to present a complete picture.
However, critics point out that this indicator is highly susceptible to manipulation – capital expenditure assumptions can be inflated to boost a company's value, and any delays in the supply of licenses, equipment, electricity, or water resources can turn “EV +1” into “+2” or “+3”, and the realization of EBIT will also be postponed accordingly.
It is reported that this week, Oracle's 1.3 gigawatt “Lighthouse” park project has experienced delays, and Project Jupiter has also declared force majeure, indicating that a “+1” outcome is merely an optimistic scenario.
At the same time, the IPO structure itself has also raised concerns among investors. Approximately half of the IPO shares are allocated to "specific existing strategic and financial investors," including NVIDIA, Coatue, Blackstone, and Jane Street; existing shareholders can sell up to 20% of their holdings from the first day of listing.
Supply pressure, coupled with pricing disputes, has made potential investors more cautious. In addition, the funds raised by IPO will primarily be used to purchase NVIDIA's GPU, in order to support Firmus's first project on Batam Island in Indonesia – NVIDIA's investment in Firmus. After the fundraising, the funds will be reinvested in NVIDIA to purchase chips, a circular structure that has raised additional doubts in the market.
Equity value below debt: from growth stocks to credit stories
What has raised the most alarm in the market is the asset-liability structure of Firmus.
According to Morningstar, the debt scale of Firmus is approximately $30 billion, which is about six times its own profit forecast. At an issue price of 11 Australian dollars, the market value of equity is around $30.4 billion, with debt and equity being roughly equal; however, if the price remains at 8.25 Australian dollars, the equity value would shrink to around $23 billion, which is about $7 billion less than its debt; if it falls to 8 Australian dollars, the gap would further widen.
In other words, even at the price level that the underwriters were striving to maintain, the market value of the equity of Firmus shareholders was already lower than the company's total debt before the first day of trading. This means that the stock is essentially a “high-leverage credit instrument with a stock code attached to it.”
On top of the 10-year U.S. Treasury yield climbing to a 24-year high of 5.36% this week, Goldman Sachs stated that the capital cost for carrying $30 billion in data center debt can only go in one direction.
Window Narrowing: Data Center IPO Faces Challenges in Entering the Market through Queuing
Firmus is the second major data center failure within three weeks. Prior to this, SoftBank's SB Energy's IPO roadshow was suspended in late September due to additional inquiries from the US Securities and Exchange Commission, as well as investors' doubts about a valuation of around $60 billion and a high dependence on a single customer, OpenAI.
There are still many data center projects in the subsequent queue for listing: DayOne in Singapore – which happens to be also the partner of Firmus on Batam Island – plans to raise up to $5 billion with a valuation of $20 billion in the United States as early as November; Switch has submitted a confidential listing application; Vantage and CyrusOne are evaluating listing options; while Nscale in the UK has just completed a pre-listing convertible bond financing of $3.36 billion.
According to Ke Yan of Shenton Research, who told Reuters, "The watershed lies in whether the demand has been contracted and implemented, whether the electricity supply is in place, or whether it remains only at the planning stage." With an actual built capacity of 42 megawatts corresponding to a pipeline capacity of 1 gigawatt, Firmus is clearly on the "planning stage" side.
From the perspective of macro investor behavior, according to a report from Goldman Sachs' Asia sales team, hedge funds have once again increased their allocation to the tech sector due to macro uncertainties. The net exposure of Mag 7 accounts for approximately 22% of Goldman Sachs' main broker accounts' total US stock exposure, which is the highest level since the beginning of 2022.
Goldman Sachs GS Research estimates that this year, global AI investment will exceed $1 trillion, with the United States and Asia collectively contributing more than 80% of the net increase in data centers. Funds are not in short supply, but the market trend is clear: investors are still betting on AI, but they prefer to do so through large technology companies with sound balance sheets and the ability to absorb large-scale capital expenditures on their own, rather than through project-based companies that are highly leveraged, have low revenues, and rely on a "planned pipeline" as their main selling point.