










The G.17 report released by the Federal Reserve Board of the United States on October 16th showed that industrial production increased by 0.7% month-on-month in September, and by 0.1% after revision in August. On the surface, this appears to be a clearly stronger monthly reading; upon closer inspection, manufacturing output grew by 0.3%, mining by 0.2%, and utilities by 3.5%. The surge in the overall index is due to both the contribution of manufacturing and the impact of fluctuations in utilities. If one were to summarize this report simply as "U.S. factories have accelerated across the board," it would blur the distinctions between industrial production and manufacturing, short-term weather-related demand, and ongoing order trends.
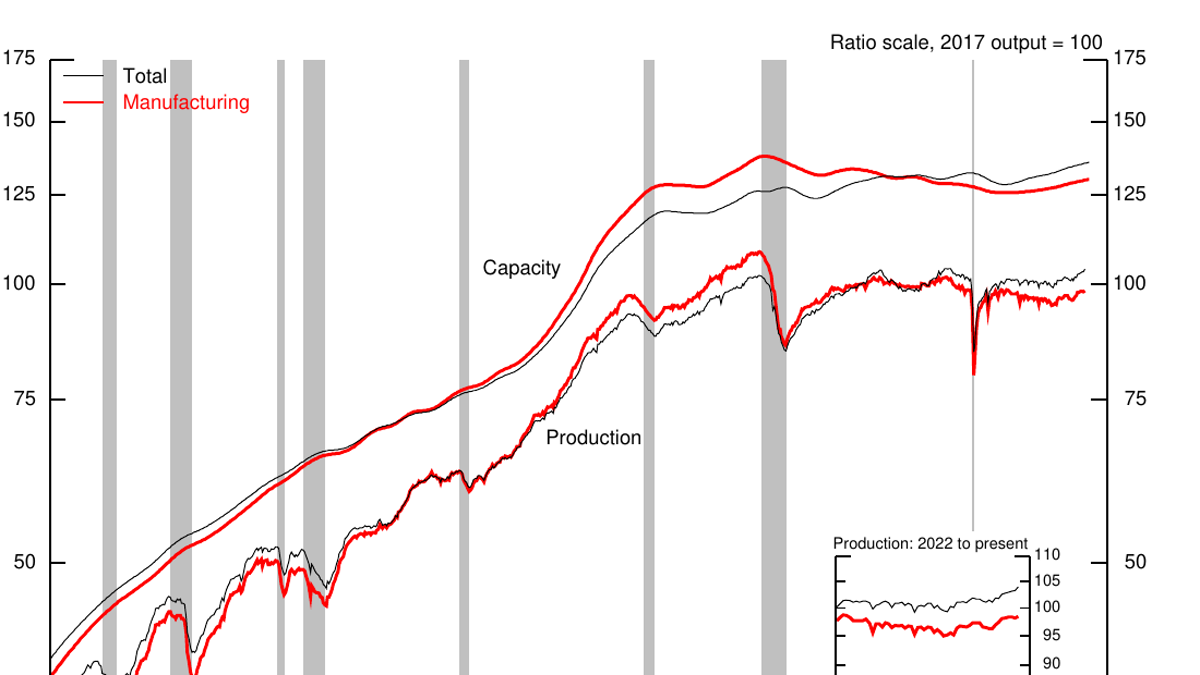
The report also shows that in September, the industrial capacity utilization rate rose to 76.9%, which is 2.5 percentage points lower than the long-term average from 1972 to 2025; the total industrial production index was 2.2% higher than the same period last year. These two pieces of information clarify the picture of growth: production activities are recovering, but not all capacity is at full capacity. For investors, businesses, and policy observers, what is most valuable is not to label 0.7% as “hot” or “cold,” but to understand which sectors are growing and whether this growth is sustainable.
Public utilities show a clear driving force, while there is still differentiation within the manufacturing sector.
The Federal Reserve defines industrial production as the actual output of manufacturing, mining, and electric power and natural gas utilities, and it is not an indicator that measures all service sector activities. In September, the utilities index grew by 3.5%, a much higher rate than that of manufacturing. Demand for electricity and natural gas is susceptible to disruptions caused by weather, seasonality, and energy consumption patterns, so a single-month increase cannot directly imply that consumer spending or corporate capital expenditures are also rising by the same amount. When assessing industrial prosperity, it is necessary to separately highlight these volatile components.
Even the 0.3% growth in the manufacturing sector is not uniform. According to a Fed report, the durable goods manufacturing index only rose slightly by 0.1%, with some sectors such as primary metals, machinery, and electrical equipment experiencing growth of at least 1%; however, automobile and parts production declined by 3.0%. The non-durable goods manufacturing sector grew by 0.4%, with support coming from chemical and printing-related industries. The coexistence of declining automobile production with growth in other equipment sectors indicates that the rhythms of supply chains, inventory levels, and end-demand may vary, and the changes in a single sector cannot represent the entire manufacturing industry.
Third-quarter data provides another layer of reference. Industrial production grew at an annual rate of 2.8%, while manufacturing only grew at an annual rate of 0.7%; the growth rate of durable goods manufacturing was higher, but that of non-durable goods manufacturing declined. The report indicates that the growth of semiconductors and related electronic components in the third quarter significantly propelled durable goods. This structure is related to recent discussions about computing power investment, however, the strength in the semiconductor sub-category does not automatically translate to all factories: equipment orders, automobile production capacity, and consumer goods output will still operate according to their respective cycles.
Capacity utilization can also help determine whether "expansion of production" is truly urgent. Overall, at 76.9%, it is lower than the long-term average, with the manufacturing sector at 75.9%, still below its long-term average; however, the mining industry has a utilization rate of 87.5%. The differences between industries suggest that companies cannot make investment decisions based on a national total figure. Resource-intensive industries may face tight constraints, while other manufacturing sectors still have idle capacity. For the market, the coexistence of output growth and idle capacity is usually more complex than a simple narrative of "economic overheating."
The meaning of interest rates and the market should be considered in conjunction with other data.
Industrial production was stronger than last month, which may improve the assessment of short-term economic activity, but it is not the only factor considered in interest rate decisions. Monetary policy is more concerned with whether inflation can decline, whether the labor market is stable, and the relative changes between demand and supply. The fluctuations in public utilities that drive up the overall index are not of the same significance as the wage and price pressures caused by the continuous expansion of manufacturing. Therefore, jumping directly from “0.7% growth in industrial production” to “the Fed will inevitably maintain high interest rates” is an incomplete chain of evidence.
It is also important to pay attention to the nature of the initial values of the data. The G.17 table labels the September readings as preliminary estimates, and historical months' data will also be revised. The Federal Reserve plans to conduct an annual revision in November, and the statistical criteria and base periods may also be adjusted. When making corporate budgets or market research, it is necessary to record the timing of the releases when comparing different versions of the same series; one cannot use later revised data to prove that the decisions made at that time were necessarily correct or wrong. Especially when the monthly increase is only a few percentage points apart, revisions can change the focus of the analysis.
For real enterprises, what is worth tracking next is not the news headlines, but whether the output, utilization rate, and new orders in their respective product categories are improving simultaneously. Machinery and equipment companies should verify whether the increase in related output comes from new projects or short-term restocking after inventory reduction; automobile suppliers need to see if the decline is related to model changes or issues in the supply chain. The financial market also requires observation of sustainability in subsequent months, as well as whether there is a divergence between manufacturing and service industries.
The message conveyed by this report is one of "a rebound in overall volume, but uneven structure." The data from September is sufficient to make a more optimistic short-term assessment of industrial activity, but it is not enough to declare that the U.S. manufacturing sector has entered a full upward cycle. By examining the components of manufacturing, utilities, and automobiles separately, and by considering capacity utilization alongside subsequent order data, we can determine whether this growth is the beginning of a sustained improvement or merely a coincidence of multiple short-term factors working in the same direction within a month. For readers, this is more useful than simply making a bet on the market direction based on a single set of data.
It is particularly important to be wary of substituting month-over-month changes for year-over-year changes. The 0.7% refers to the change in September compared to August, while the 2.2% refers to the change in September compared to a year ago; the 2.8% for the third quarter is then converted into a quarterly rate on an annual basis. These are not three figures that can be simply added together to represent “growth contributions.” If the media presents figures from different time periods side by side without clarifying the basis for comparison, readers may mistakenly assume that industrial expansion has been more vigorous than it actually is. When corporate management uses this report to plan future production capacity, they should also align it with their own sales and delivery cycles before deciding which figure is the most informative.
Another subsequent observation is regarding the direction of revision. If the readings for automobiles, machinery, and public utilities gradually converge over the coming months, the strength in the September index may be more of a temporary rebound; only if multiple sub-indicators of manufacturing continue to improve will there be a better reason to discuss a widespread recovery. Before evidence is available, it is more accurate to describe this month as "a positive but uneven reading of production recovery" than to declare that the economic cycle has already turned around.
Source: Federal Reserve, Statistical Bulletin of October 16, 2026 G.17 https :// www.federalreserve.gov / releases / g17 /20261016/ g17.pdf.