Key Points
- AI Momentum trading has cooled down sharply, with all the gains from high-beta momentum portfolios being completely eroded within the year. SOX has recorded its worst performance relative to the S&P 500 in over 20 years across the past nine trading days.
- Meta financial reports exacerbate market concerns about the return on capital expenditure of AI; hedge funds accelerate reduction of risk exposure, and systematic strategies for short-selling leverage rise to a five-year high
- At the same time, funds are shifting towards assets with lower volatility and higher profit quality, and defensive strategies are once again gaining strength.
On October 23rd, concerns about the investment returns of AI further intensified in the market. Goldman Sachs' trading desk described this round of concentrated selling of AI and the semiconductor sector as "the worst performance since the DeepSeek shock day," and the debate over AI investment costs and returns triggered by the Meta financial reports became a catalyst for the acceleration of this downward trend.
Selling pressure is spreading from the stock price level to investment portfolios. Data from Goldman Sachs Prime shows that the net long-short leverage ratio of hedge funds has dropped to the 1st percentile of the past year, and the global AI stock long-short ratio has also fallen to the 6th percentile; at the same time, data from UBS indicates that the short-selling leverage ratio of systematic strategies has risen to the 99th percentile of the past five years.
The market style has also changed accordingly. As high-beta, high-kinetic trading fades away, factors related to low volatility and profit quality have once again strengthened. Funds have begun to shift from pursuing highly volatile assets to strategies that place more emphasis on defensiveness and the certainty of profits. Whether AI trading can regain support depends on the market's re-evaluation of the returns on massive capital expenditures.
All year-long gains have been wiped out, with momentum trading suffering a heavy setback.
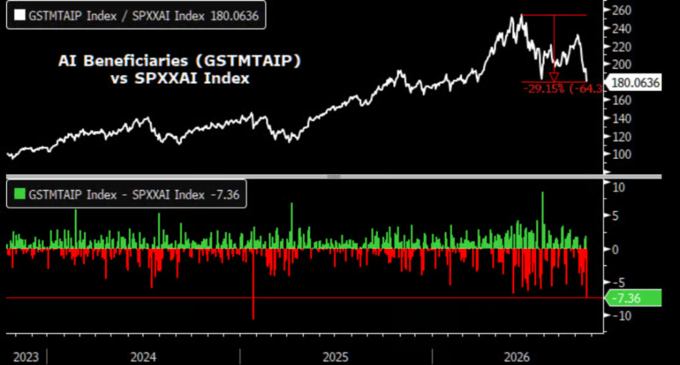
Data shows that Goldman Sachs' high-beta momentum pairing portfolio (GS High Beta Momentum Pair) once achieved a year-on-year increase of about 70% at its peak in June, but by October, it had fully retraced that gain. The unconstrained momentum strategy (Unconstrained Momentum) is also experiencing the most severe pullback since the global financial crisis, second only to the period during the pandemic impact.
Goldman Sachs trading desk stated that last Thursday, stocks that were strong earlier in the week once again faced concentrated selling, with AI and the semiconductor sector performing particularly poorly. The Meta earnings report exacerbated market concerns regarding the return on capital expenditure for AI, and investors began to re-evaluate whether massive investments could translate into corresponding returns.
The decline in the semiconductor sector was particularly prominent. According to data from Peter Callahan, within the 9 trading days starting from October 12th, SOX fell by approximately 13% compared to the S&P 500, setting a new record for the largest relative decline over the same time period in over 20 years and placing it in the 1st percentile of historical distributions.
The continuous decline has also pushed SOX near the 200-day moving average, which is the first time this index has touched this key technical level since June 2025. Whether this moving average can provide support will become an important indicator to observe whether the adjustment in the semiconductor sector will deepen further.
Hedge funds are accelerating risk reduction, with short-selling leverage reaching high levels
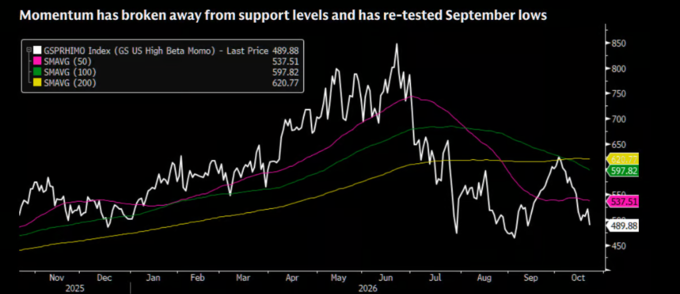
According to Goldman Sachs’ Prime data, the fundamental long-short net leverage ratio decreased by 3.1 percentage points this month to 49.4%, placing it in the 1st percentile of the distribution over the past year and the 4th percentile over the past three years, indicating that hedge funds are significantly reducing their net market exposure.
The global AI stock long-short ratio has dropped to the 6th percentile of the past year, and the exposure to the momentum factor has also fallen to its lowest level since late June 2025. However, looking at the five-year historical distribution, the exposure to the momentum factor is still at the 73rd percentile and has not yet reached a long-term low.
The short-selling side continues to heat up. According to UBS data, the leverage ratio of systematic short-selling strategies has approached its highest level in the past five years, sitting at the 99th percentile. However, the long-selling leverage ratio has also risen to the 94th percentile, indicating that both long and short sides are using high leverage. The market is not simply shifting towards a purely bearish outlook but is rather readjusting positions and risk exposures.
Low volatility and improving profit quality lead to a shift in funds towards a defensive strategy.
As high-beta momentum trading fades, low-volatility factors have recently performed strongly, once again becoming the preferred allocation direction for funds; the quality of earnings factors have also strengthened. According to Goldman Sachs' Prime data, their exposure has risen to a five-year high.
Goldman Sachs' trading desk noted that, after adjusting for industry, sector, and factor neutrality, the Goldman Sachs Quality Index has risen by about 20% over the past three months, which is equivalent to a performance of about 13 times volatility, mainly driven by the significant underperformance of low-quality stocks.
This change indicates that funds are shifting from assets that pursue high growth and high resilience to targets that place more emphasis on the quality of earnings and the certainty of performance. As investors re-evaluate the cost, return, and realization cycle of AI capital expenditures, the revaluation of related assets is likely to continue.