The trend of AI transactions is changing.
In the past, as long as a stock was associated with AI, it could enjoy generous valuations from the market. However, with concerns about cash flow arising from the massive capital expenditures of tech giants, and following Intel's disappointing performance forecasts that led to heavy selling, investors have begun to re-evaluate the growth logic of the AI industry chain.
For Supermicro Semiconductor ( AMD ), which is set to release its financial report after the market closes on Tuesday, the market's expectations are no longer just for a good performance; rather, it must demonstrate with strong enough results and more aggressive future prospects that it is still worthy of its high valuation.
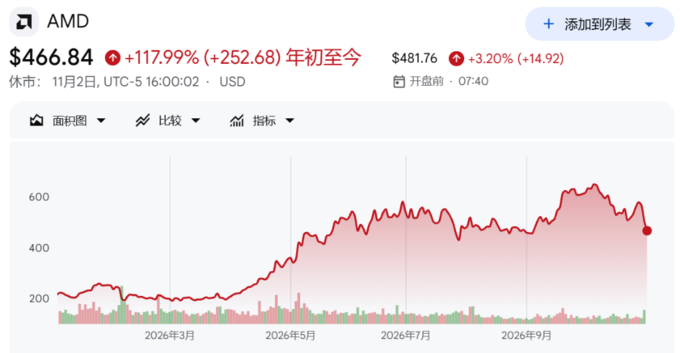
Since the beginning of this year, the stock price of AMD has risen by approximately 118%, far exceeding the 46% increase in the Philadelphia Semiconductor Index. However, as the trading sentiment for AI suddenly cooled down, this upward trend has also put AMD in a delicate position: the higher the growth expectations, the smaller the margin for error in performance.
Allspring Global Investments Portfolio Manager Neville Javeri stated bluntly that to maintain the current upward trend, "it's not just about exceeding expectations, but significantly exceeding them, accompanied by quite strong performance guidance. Mild performance is no longer sufficient."
Intel tumbles, AMD faces the same test
Intel's experience has already sounded the alarm for AMD.
Before announcing its financial results, Intel was one of the brightest-performing chip stocks in the U.S. stock market this year. AI Infrastructure construction drove demand for CPU, and the company's stock price soared by 150% in 2026.
However, the weak performance guidance completely changed market sentiment.
Last Friday, Intel's stock price experienced the most severe one-day decline since 1982. By the close of trading on Monday, its year-to-date gain had significantly narrowed from 150% to 63%.
AMD was also not spared from this sell-off.
Last Friday, the stock price of AMD fell by 10% in a single day, with a cumulative decline of over 17% in October. Nevertheless, its year-to-date increase is still as high as 118%, significantly outperforming the semiconductor sector.
The market logic faced by both companies is quite similar: AI demand once drove a significant rise in stock prices, but when investors begin to question whether the growth can be sustained, the valuations that were originally based on optimistic expectations may quickly come under pressure.
The bigger problem is that the market's attitude towards expenditures related to AI is also changing.
In the past two weeks, the massive capital expenditure plans of giants such as Alphabet, Meta, and Amazon have raised concerns in the market. Investors have begun to wonder whether these investments are eroding cash flows, and whether the infrastructure construction of AI can continue to expand at the current pace.
For chip companies that rely on the continuous growth of investments represented by AI, this shift in sentiment undoubtedly constitutes pressure.
The stock price has risen by 118%, and the performance threshold for AMD has also been raised.
Fundamentally speaking, AMD is not lacking in growth support.
Wall Street expects that AMD's third-quarter profits will increase by 92% year-on-year, and revenue will grow by 41% year-on-year. Analysts also predict that these two indicators will continue to grow in 2027.
The company CEO Su Zifeng also stated last month that the demand for chips will be “very high” in the coming years, exceeding supply capacity.
But the problem is that the stock price has already reflected quite optimistic expectations in advance.
As of now, the price-earnings ratio of AMD corresponding to its expected earnings for the next 12 months is about 32 times, ranking fourth among the components of the Philadelphia Semiconductor Index. Although this valuation is lower than the peak of 56 times reached on June 30th of this year, it is still considered relatively expensive.
Historically, AMD has had an average expected price-earnings ratio of around 34 times since 2017.
This means that even if the performance of AMD meets or slightly exceeds market expectations, it may not be sufficient to drive the stock price to continue rising.
What the market really wants to see is further acceleration in growth.
In the past three months, Wall Street has raised its earnings forecast for AMD for 2027 by 23%, and its revenue forecast by 14%. The forecasts for 2028 have also seen a more substantial increase. According to the average target prices compiled by Bloomberg from analysts, AMD still has about 40% room for growth in the next 12 months.
However, the expectation of continuous upward revisions also means that the market consensus before the financial report has become more aggressive.
Once performance or targets fail to meet this threshold, the stock price may face dual adjustments in valuation and expectations.
Muse Can it become AMD's 'outstanding engine'?
AMD still has one important growth catalyst: the AI intelligent entity.
With the rapid development of the AI agent, the role of CPU in the AI infrastructure is once again coming into focus. Unlike GPU, which is primarily responsible for the training and inference tasks of the AI model, CPU plays a crucial role in coordination and control during the operation of the agent.
The Muse of Meta was successful, further enhancing market attention to this trend.
According to data compiled by Bloomberg, CPU contributed nearly a quarter of AMD's revenue in 2025. Meta is AMD's second-largest customer, accounting for 5.5% of its revenue.
The popularity of Muse has also prompted some analysts to raise their target prices for AMD. Analyst Kevin Cassidy even listed AMD as the stock they are most optimistic about before the financial report.
Javeri believes that investors need to see evidence of accelerated growth, and Muse is undoubtedly a credible catalyst.
If the AI intelligent entity drives further growth in demand for CPU, then AMD indeed has the opportunity to transition from good growth to ultra-high-speed growth.
But this is still an expectation that requires performance verification.
Whether the rise of AI intelligent agents can be continuously translated into actual orders, revenue, and profit growth for AMD remains an issue that the market needs to observe. At the same time, whether AI infrastructure spending will slow down will also directly affect the sustainability of chip demand.
Wall Street is no longer willing to pay for the "growth story"
Changes in market sentiment have begun to affect investors' actual trading decisions.
Wealth Consulting Group Chief Investment Officer Jim Worden stated that due to the uncertain macroeconomic environment and the relatively high valuation of AMD, he has exited his positions in AMD, but continues to hold shares in other chip companies such as NVIDIA, Broadcom, and TSMC.
He pointed out that AMD indeed has the potential to move from good growth to super-high-speed growth, and factors such as Muse could also act as accelerators, but he is not at ease with the current valuation, “there are simply too many problems.”
This statement reveals the core contradictions currently faced by AMD.
On one hand, the growth in demand for AI and CPU, along with the expectation of a supply shortage in the coming years, provides a fundamental basis for the company's continued growth; on the other hand, the sustainability of AI capital expenditures, market valuations, and investors' sensitivity to disappointing performance are creating increasing pressure.
The financial report of AMD is no longer just a test of revenue and profits; it is also a verification of the entire trading logic of AI.
If the company can deliver significantly better-than-expected performance and provide strong future guidance, the market may once again embrace its growth story.
However, if one merely submits a transcript that meets expectations, it will be difficult to maintain market confidence against the backdrop of Intel's plummeting stock prices and the growing concerns regarding AI expenditures.
When investors begin to demand that AI companies prove that their investments can be converted into returns, what AMD needs to answer is no longer just “how fast the growth is,” but “to what extent the growth can continue to be fast.”