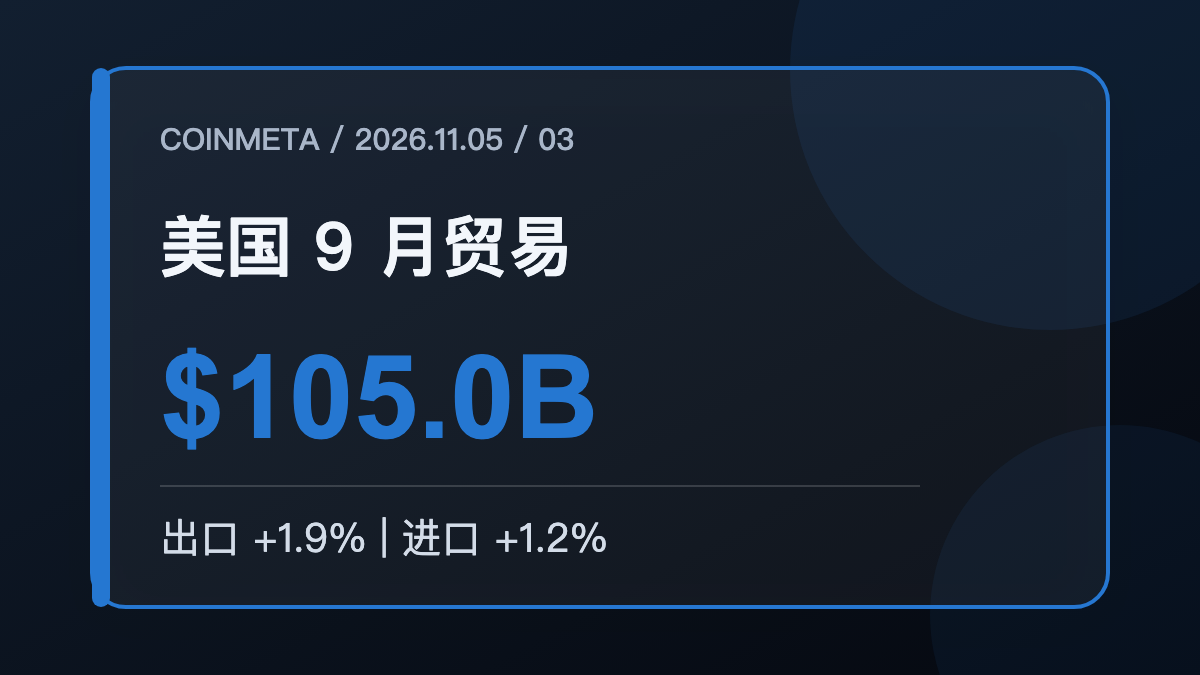
In September, the United States recorded a trade deficit of $105 billion in goods and services, which was $700 million less than the revised figure for August, representing a decrease of only 0.7%. On the surface, a smaller trade deficit might suggest an improvement in external demand, but the same official data provides a more complex picture: exports grew by 1.9% to $321.5 billion, and imports also increased by 1.2% to $426.6 billion. The narrowing of the trade deficit is not due to a decline in imports, but rather because the increase in exports was slightly higher than that in imports. For the market, this is more significant than just a headline stating a “decrease in the trade deficit.”
Both sides have risen, and only then has the difference slightly narrowed.
In September, exports increased by $5.8 billion, and imports increased by $5.2 billion. The difference between the two was only about $600 million, which ultimately resulted in a reduction of the trade deficit by $700 million. The trade deficit in goods decreased by $700 million to $135.9 billion, while the service surplus slightly fell to $30.9 billion. In other words, the main improvement came from the goods side, rather than a sudden strengthening of service trade.
This structure indicates that domestic demand in the United States still has resilience. If the economy weakens significantly, imports tend to contract first; however, imports continued to expand in September, suggesting that businesses and consumers are still purchasing overseas capital goods, consumer goods, and services. The simultaneous growth in exports indicates that external markets are also absorbing more American goods and services. Therefore, trade data is not simply "good" or "bad"; rather, there is activity in both directions with limited changes in the trade balance.
Computers and accessories drive up the import of capital goods
Commodity imports increased, with capital goods rising by $11.6 billion, which is the most notable contributor. Computer imports increased by $7.6 billion, and computer accessories by $5.7 billion, while semiconductor imports decreased by $1.2 billion. These figures easily bring to mind investments in data centers and artificial intelligence, but official trade statistics only describe the flow of goods and cannot directly prove that all of this increase comes from AI construction. A more cautious interpretation is that imports related to corporate equipment have significantly risen, indicating that the capital expenditure chain is still absorbing a large amount of overseas supply.
Consumption goods imports increased by $2.4 billion, of which pharmaceutical preparations saw an increase of $2.9 billion. Imports of industrial supplies and materials decreased by $3.7 billion, and crude oil imports fell by $1.3 billion. The divergent trends among different categories indicate that the overall import growth was not uniform; it was concentrated in capital goods and certain consumer goods. When analyzing inflation, it is also important to note that these data are seasonally adjusted but do not account for price changes. The increase in nominal amounts may reflect both quantity and price factors.
Export growth also has its own structure.
Commodity exports increased by $5.1 billion to $211 billion. Capital goods increased by $3.8 billion, of which computers increased by $1.3 billion, computer accessories by $0.8 billion, and civil aircraft by $0.7 billion; food, feed, and beverages increased by $1.9 billion, with soybeans increasing by $1.3 billion. Consumer goods increased by $0.8 billion, and pharmaceutical preparations contributed $0.7 billion. Industrial supplies and materials decreased by $1 billion, non-monetary gold fell by $3.4 billion, and crude oil increased by $1.2 billion.
Service exports increased by $700 million to $110.5 billion, with travel services growing by $300 million and intellectual property royalties rising by $100 million. Service imports increased by $800 million to $79.7 billion, of which travel imports increased by $500 million and transportation imports by $200 million. The fact that the service surplus did not expand means that the improvement in the deficit this month cannot be mainly attributed to the traditional service trade advantages of the United States.
Improvements within the year coexist with deterioration over the past three months.
In the first nine months of this year, the trade deficit in goods and services decreased by $92.4 billion compared to the same period last year, a reduction of 12.2%; exports increased by $297.3 billion, with a growth rate of 11.6%, and imports increased by $204.9 billion, with a growth rate of 6.2%. Over the course of the year, exports have shown a significantly faster growth rate than imports, which is the main source of the improvement in the trade deficit.
However, the three-month moving average provides another indication: as of September, the three-month average deficit increased by $11.3 billion to $101.2 billion. Average exports increased by $1.4 billion to $316 billion, while average imports increased by $12.7 billion to $417.2 billion. The slight decrease in the monthly deficit did not reverse the trend of increasing deficits in recent months. Investors who only focus on the 0.7% decline in September may underestimate the continued strength on the import side.
The real trade balance has actually expanded.
In September 2017, the actual trade deficit in goods, calculated in US dollars, increased by $3.5 billion, representing a growth of 3.0% to reach $119.5 billion. Actual exports of goods grew by only 0.1% to $152.2 billion, while actual imports of goods increased by 1.4% to $271.6 billion. The trade deficit in goods in nominal terms improved slightly after adjustments to the balance of payments, but in real terms it expanded. The difference is related to adjustments for non-monetary gold.
This reminds the market that trade data is influenced not only by volume but also by prices and statistical adjustments. When assessing its contribution to gross domestic product (GDP), one cannot simply transfer the changes in the nominal deficit directly. A more reliable approach is to consider actual exports, actual imports, and subsequent revisions to observe whether net exports actually support or drag down economic growth.
What the market really needs to look at is not just a single arrow (indicator).
What is most noteworthy about the September data is not the "decrease" in the trade deficit, but rather the strong import volume, the prominent flow of capital goods, and the expansion of the average trade deficit over the past three months. This can be interpreted as both active demand from the United States and continued corporate investment, but it also implies that net exports may not be able to sustain growth in the long term. In the coming months, if imports of computers and accessories remain high while export growth fails to keep up, any slight improvement in a single month could easily be reversed.
Trade figures are often presented as a single directional arrow, but this report is more like a slice of the economy: corporate equipment demand, pharmaceutical consumption, energy flows, travel services, and gold adjustments all come into play simultaneously. The key to understanding it is to separate exports and imports first, and then discuss the difference. 105 billion US dollars is not the answer; rather, it is the result of subtracting one from another six different demand scenarios.