

NVIDIA's stock price has suffered a heavy setback, with its forward price-earnings ratio dropping to around 12 times, the lowest level since 2012. However, despite the valuation falling to a historical low, this has not led to a consensus of bullish sentiment on Wall Street. With the resignation of founder and CEO Jensen Huang, there is a clear divergence in market confidence regarding this AI chip giant.
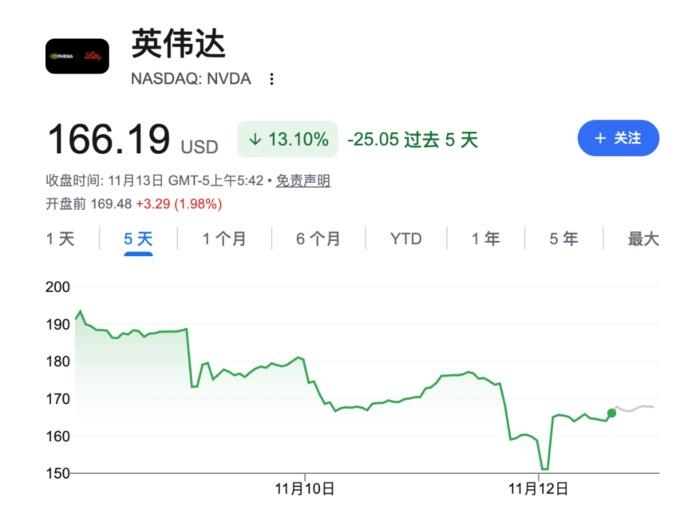
On Thursday, NVIDIA's stock price tumbled by more than 14% in the early session, but then gradually recovered under the impetus of emergency public relations efforts and buying at lower levels. In the end, the stock closed down 4.34% at $166.19. Compared to the peak of $243.37 set on October 6, the stock has seen a cumulative decline of over 30%.
Amidst the sharp drop in stock prices, retail investors are aggressively buying on dips. Data from Vanda Research shows that in the first half hour after trading began on Thursday, retail investors bought a net of $111 million worth of NVIDIA shares, setting a record for the same period in history. Well-known bulls such as those from Tom Lee, Freedom Capital Markets, and Paul Meeks also publicly called for purchases, believing that the current valuation is already attractive.
But on the other side, some institutions on Wall Street are withdrawing. Bernstein downgraded NVIDIA's rating from 'Buy' to 'Market Perform', and cut the target price from $400 to $200; although Goldman Sachs maintained its 'Buy' rating, it lowered the target price from $300 to $220. Well-known bearish analyst Michael Burry even warned that NVIDIA's bulls might want to take their profits as soon as possible during the next earnings reporting period.
The focus of this bull-bear game is no longer just whether the demand for AI chips can continue, but whether NVIDIA can maintain its original technological leadership and organizational efficiency after Jensen Huang leaves, as well as the AI industry financing ecosystem that he led in building.
Retail investors are making record purchases at bottom levels, and well-known bulls such as Tom Lee are publicly calling for buying.
On Thursday, NVIDIA's stock price initially fell to $148.80, a decrease of over 14% from the previous trading day's closing price, and also broke below its 52-week low of $164.27. Thereafter, the stock price gradually rebounded, but ultimately closed down 4.34% at $166.19. Although the decline narrowed, the stock is still down by about 32% from its historical high of $243.37 set on October 6th.
The sharp drop in stock prices has instead sparked retail investors' enthusiasm for buying at low points. According to Vanda Research data, within the first half hour of trading on Thursday, retail investors bought a net amount of $111 million in NVIDIA shares, setting a new record for this time period.
Fidelity Investments ( Fidelity Investments ) platform data shows that as of noon on Thursday Eastern Time, customers had submitted a total of 394,818 buy orders for NVIDIA, while there were only 80,088 sell orders. The number of buy orders even exceeded the combined total of buy orders for the stocks ranked second to tenth in trading volume on that day.
Well-known investors also expressed a bullish stance at this time. Tom Lee, Freedom Capital Markets, the technical research directors of Fundstrat Global Advisors, and Paul Meeks all publicly hold a positive view on NVIDIA. Meeks believes that the current valuation is already unreasonably low and has indicated that they will make large-scale purchases.
Nationwide Financial Chief Market Strategist Mark Hackett believes that investors have developed a habit of repeatedly buying at lows, and each successful attempt further reinforces this behavior. He also pointed out that the long-term prospects for AI remain positive.
Valuation drops to a 14-year low, orders backlogged until 2028 to provide support
The core logic supporting the current bottom-fishing perspective is that NVIDIA's order visibility, product roadmap, and profitability have not undergone significant changes despite the decline in stock price.
Piper Sandler Analyst David O ' Connor Maintains an overweight rating with a target price of $300. He pointed out that NVIDIA's orders for 2027 have been sold out, and the same is largely true for 2028 as well; current discussions with clients are regarding business for 2029 and beyond. Wolfe Analyst Chris Caso also believes that at least until 2028, NVIDIA's fundamentals and profitability will not be significantly affected.
RBC It is estimated that the current demand for chips exceeds supply by about 50%; JPMorgan Chase points out that the mass production ramp-up paths for subsequent products such as Vera Rubin, Rubin Ultra, and Feynman have been clarified.
The latest quarterly results also support this judgment: NVIDIA's revenue reached $96.2 billion, a year-on-year increase of 106%; data center revenue grew by 117% to $89 billion, and the company expects revenue of about $108 billion in the next quarter.
What investors are more concerned about is valuation. As the stock price continues to correct, NVIDIA's forward price-earnings ratio has dropped to around 12 times, the lowest level since 2012. According to the profit forecasts of different institutions, the expected price-earnings ratio for its fiscal year 2027 is about 10 times, and the consensus price-earnings ratio for 2028 is even only about 7 times.
Raymond James maintains a strong buy rating and a target price of $515, believing that there has been almost no change in NVIDIA's fundamentals, and that the stock price has entered an oversold area.
However, the market's bullish sentiment towards NVIDIA is not unanimous. According to TipRanks data, among 27 analysts, 10 still maintain a 'hold' rating, with an overall rating of 'moderate buy', and an average target price of around $257. Fourteen investment banks have given an average target price of about $260.
Wall Street begins to reprice: Downgrades and target prices appear one after another
In contrast to some investors who are actively buying at low prices, more and more institutions on Wall Street have begun to factor in the uncertainty caused by Jensen Huang's resignation when valuing NVIDIA.
Bernstein Analyst Stacy Rasgon has significantly reduced the target price from $400 to $200. He believes that the problems NVIDIA is facing may be more than what have been exposed so far, and uses the metaphor of "finding two ants in the kitchen" to suggest that there may be more issues to come to light in the future.
Goldman Sachs analyst James Schneider has maintained a buy rating, but has also lowered the target price from $300 to $220. It is worth noting that Goldman Sachs has not reduced its earnings per share forecast; instead, it has tightened the valuation multiple from 30 times to 22 times to reflect the uncertainties associated with the management transition period.
Well-known bear Michael Burry is even more pessimistic. He acknowledges that the mechanical buying from index funds and retirement accounts has helped NVIDIA absorb some of the selling pressure, but he believes that the real impact of Jensen Huang's resignation on the business may take longer to become apparent. He warns that NVIDIA's bulls might yet have another better opportunity to exit, and he says bluntly: "NVIDIA's bulls will have another great chance to get out. Get out."
Burry also questioned the company's succession arrangements: about 60 senior executives report directly to Jensen Huang, yet there are almost no obvious internal successors.
There are also disagreements among institutions regarding the judgment of the stock price bottom. Cantor, Piper, KeyBanc, and Citibank all consider around $150 to be a reasonable support level, which corresponds to approximately 9 to 11 times the expected earnings per share for 2027. RBC suggests a lower scenario of $100, which corresponds to about 6 times the expected earnings per share for 2027, below NVIDIA's lowest valuation point over the past five years.
Jensen Huang leaves two major challenges: management architecture and financing ecosystem
Compared to short-term orders and profits, the impact of Jensen Huang's resignation on NVIDIA's long-term competitiveness is more difficult to quantify, mainly reflected in two aspects: organizational management and industrial financing.
Firstly, there is the organizational structure. Analyst Jay Goldberg from Seaport stated bluntly: “In simple terms, no one can wear Jensen Huang’s jacket.” Wells Fargo also pointed out that about 60 executives report directly to Jensen Huang, and such a flat structure is not sustainable nor easy to replicate, which may affect internal coordination efficiency and the pace of product launches.
JPMorgan Chase believes that the interim management team may be able to maintain the current product roadmap in the short term, but in two to three years, the real test will be whether the new management can identify the next technological inflection point in the field of accelerated computing and continue to build platforms and ecosystems that go beyond the chips themselves.
Secondly, there is the financing ecosystem. Over the past few years, Jensen Huang has utilized NVIDIA's free cash flow of approximately $50 to $60 billion per quarter to provide financial support for companies such as OpenAI, Anthropic, xAI, and CoreWeave through methods such as equity investments, asset endorsements, and supplier prepayments.
Analyst Tim Arcuri believes that this is one of the greatest potential impacts of Jensen Huang's resignation. Even if the new leadership decides to continue with a similar strategy, there may still be a period of pause. If as much as $50 billion in funds no longer flows into the AI industry chain each quarter, the financing environment for related companies could deteriorate rapidly.
This risk coincides with an increase in interest rates and a tightening of liquidity in the credit market. On the day of the announcement, the stock price of CoreWeave fell by more than 11% before trading began, while the company was at that time promoting an investment-grade loan worth over $4 billion to the market.
Seaport also pointed out that a financing platform plan previously announced by Jensen Huang, involving six private equity funds and totaling $500 billion in scale, has not yet seen the final signing of related contracts. Without Jensen Huang's drive, there are doubts as to whether this plan can continue to progress.
Regulatory pressures combined with intensified competition pose a test to NVIDIA's moat.
Jensen Huang's resignation has not alleviated the regulatory pressures faced by NVIDIA. The independent investigation conducted by the board of directors, chaired by attorneys from Wachtell law firm Joon Kim, is still ongoing, and the investigation by the US Department of Justice Megaspeed has also not concluded. The House of Representatives has requested a closed-door briefing to be held on November 18th, while senators Warren and Coons have demanded that NVIDIA submit relevant records.
Export controls are also a focal point of market concern. Goldman Sachs estimates that NVIDIA's sales exposure outside the United States is about 11%; UBS believes that stricter export regulations may affect the company's shipments to places such as Singapore and Malaysia, with about 10% of revenue at risk. However, Wolfe thinks that the market's concerns about export controls may be exaggerated.
At the same time, competitors may benefit from the uncertainties faced by NVIDIA. BNP Paribas, Seaport, and William Blair all identify AMD and Broadcom as potential beneficiaries, suggesting that hyperscalers and AI laboratories may be more proactive in diversifying their chip supply sources. BNP Paribas expects that by 2030, custom chips could account for nearly three-quarters of the shipments of AI accelerators.
William Blair also pointed out that the competitive barriers in the CUDA ecosystem largely stem from the cost of code migration, but the AI programming assistant is lowering this barrier. Anthropic disclosed in its IPO roadshow materials that the adaptation of its Claude Mythos Preview model for prompt processing on AMD MI355X chips only took about three days, whereas in the past, similar tasks usually required 6 to 12 months.
Counterpoint Research believes that Jensen Huang previously incorporated the entire AI supply chain into the annual product iteration cycle. With this unified rhythm possibly changing, the AI hardware industry may enter an era of 'multi-speed parallelism', and supply chain partners will also need to readjust their product planning and investment schedules.
The successor remains undecided, and the financial report has become the next challenge.
At present, there is still no clear answer to the succession issue of NVIDIA CEO. According to an analysis released on November 12th by the forecasting market analysis institution The Action Network, internal executive Ian Buck leads with a implied probability of 35.5%, temporary CEO Colette Kress ranks second with 25.5%, Arm CEO Ren and Haas are in third place with 9.1% each, and the probability for AMD CEO Lisa Su is 2.4%. (The above estimates combine the market forecasts of Kalshi and Polymarket and are weighted based on the historical forecast accuracy of each platform.)
Ian Buck has worked at NVIDIA for 22 years, responsible for hyperscale computing and high-performance computing services, and is considered the core creator of the CUDA architecture. As for external candidates, Arm CEO Ren, Haas, AMD CEO Lisa Su, as well as Micron Technology's CEO Sanjay Mehrotra have also been mentioned by the media.
NVIDIA is scheduled to release its third-quarter financial report on November 17th. The market will not only be focusing on revenue, orders, and guidance for the next quarter but will also closely observe how the interim management team will explain the strategic arrangements following Jensen Huang's resignation.
Mark Hackett pointed out that with the new management just taking office, it is difficult to gain the full trust of the market based on just one financial report conference call. In addition, Anthropic is expected to launch IPO later next week, which will also become an important window to observe the investment sentiment in the AI industry.
For NVIDIA, having orders scheduled until 2028 and continuous profit growth may be sufficient to support the current bottom-fishing logic of some investors. However, what the market really needs to reprice is whether this AI chip giant will be able to continue to maintain the technological, organizational, and industrial ecosystem advantages it has established in the past after Jensen Huang leaves.