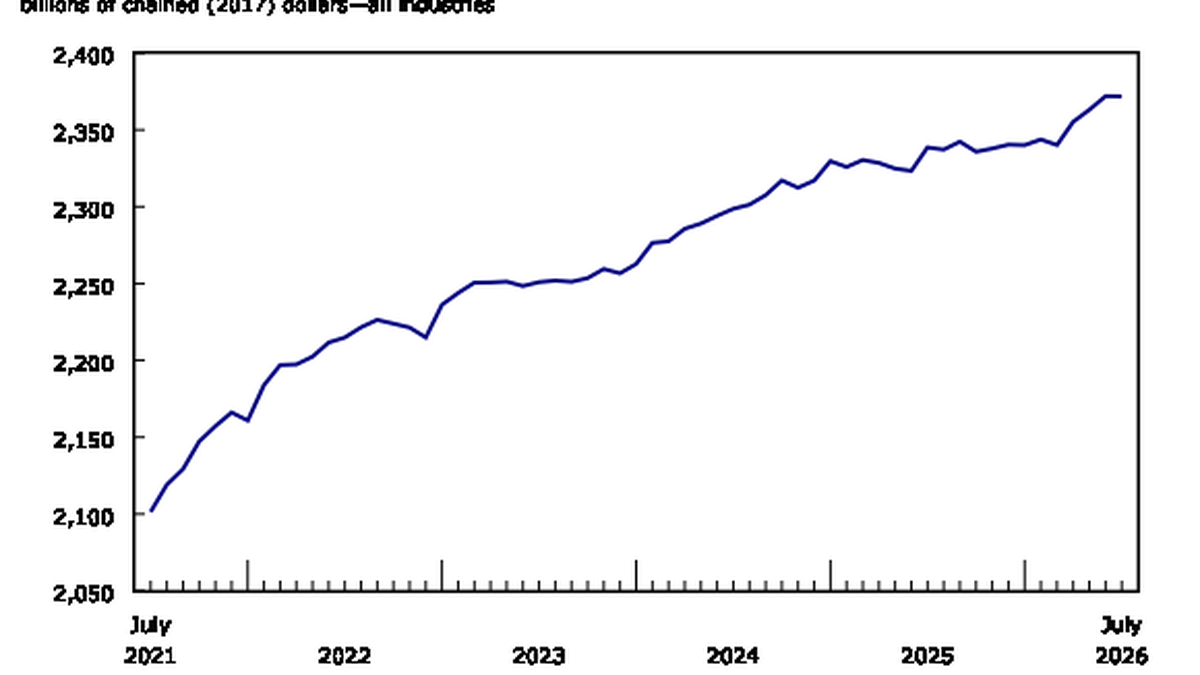


The monthly GDP calculated by industry, released by Statistics Canada on September 29th, showed that in July the actual GDP was essentially flat on a month-on-month basis, which rounded to 0.0%. Ten industries experienced expansion, while another ten did not show any growth. It would be inaccurate to describe this result as a “stall in the Canadian economy”: construction, public utilities, and some service sectors continued to increase output; however, calling it a “steady recovery” is also lacking in evidence, as manufacturing, mining, retail, and wholesale industries were moving in the opposite direction. The overall figure appears calm on the surface, but beneath that there are clear tensions among different industries.
This data measures the actual changes in added value across various industries and has been seasonally adjusted. It represents not corporate turnover nor household income. The statistical bureau specifically reminds that it differs from the quarterly GDP calculated based on consumption, investment, and net exports in terms of concept and methodology. The total result of 0.0% in July cannot be directly used to replace the second-quarter expenditure-based GDP, nor can a month's flat trend be used to infer the annual growth rate. What readers really need to see is which industries are contributing positively and which ones are offsetting these gains.
Construction costs have risen for four consecutive months, and the heatwave has also pushed up electricity demand.
In July, the construction industry grew by 1.3%, marking the fourth consecutive month of expansion, which offset some of the decline at the end of 2025 and the beginning of this year. Non-residential construction saw a growth of 2.9%, the largest single-month increase for this sub-sector since January 2022; the statistics bureau attributed part of this activity to the construction of a new hospital in Ontario. Engineering and other construction activities grew by 1.5%, while residential construction grew by 0.9%, with the latter driven by home renovations and the construction of various types of new residences. These figures indicate that the construction sector is making up for lost ground, but the impetus from one hospital project should not be interpreted as a comprehensive strengthening of the national commercial real estate market.
Public utilities grew by 1.7%, reversing the contraction in June. Electricity production, transmission, and distribution increased by 1.7%, while natural gas distribution increased by 2.9%. The Statistics Bureau noted that heatwaves occurred in multiple regions of Canada in July, which drove up electricity demand. In other words, the growth in the electricity industry is partly due to weather conditions, rather than a sudden increase in businesses' long-term investment intentions. Once temperatures cool down in the future, this supporting factor may weaken. To observe the economic fundamentals, it will be necessary to account for these weather disruptions.
There are also bright spots in the service sector. Professional, scientific, and technical services grew by 0.3%, with construction, engineering, and related services increasing by 0.5%, in line with the expansion of construction activities. The real estate and leasing industry grew by 0.2%, and the accommodation and catering industry grew by 0.8%; accommodation services alone rose by 1.6%, which coincided with the increase in international travelers entering Canada during the same period. These sectors supported the overall growth, but they were not sufficient to fully fill the gap on the side of goods production and physical consumption.
Both manufacturing and retail sales are weakening. The sign of zero growth can be seen from here.
Manufacturing declined by 0.9% in July, marking the first decline in four months. The production of petroleum and coal products fell by 5.7%, and refining activities decreased by 6.2%; according to the statistics bureau, an unexpected shutdown of a refinery in southwestern Ontario reduced the production of gasoline, diesel, and aviation fuel. Machinery manufacturing also saw a 5.1% decline, as did the production of metal products and food. Since the refinery shutdown was a specific supply disruption, it cannot be attributed solely to a collapse in demand for orders; however, with multiple industries weakening at the same time, it cannot be simply dismissed as a "temporary accident."
Mining, quarrying, and oil and gas extraction decreased by 0.5%, with potash fertilizer extraction falling by 6.4%, marking the largest single-month decline since September 2025. This coincided with a weakening of production and exports in Saskatchewan. Retail trade declined by 1.0%, almost offsetting the growth seen in June; activity at gas stations and fuel sellers decreased by 3.5%, while comprehensive retail sales, including department stores, fell by 2.2%. The Statistics Bureau mentioned a rapid rise in gasoline prices during the tourist peak season, which could affect purchase volumes and distribution of consumption. However, the decline in added value across industries does not necessarily mean that all retailers' revenues will decrease by the same proportion. Wholesale trade also fell by 0.4%, with wholesale related to equipment and daily necessities being particularly affected.
The statistics bureau also provided an early estimate for August indicating that the actual GDP in various industries "may grow by 0.2%": mining and retail sectors showed recovery, but this was partially offset by declines in oil and gas extraction. This is only preliminary information and not the official August figures; the official release of August data and updated estimates is scheduled for October 30th. Describing this early estimate as "a rebound in August" could once again lead to confusion. Canada's monthly GDP figures will also be revised due to new surveys, tax data, and seasonal adjustments, with this round of data even being retroactively revised back to January 2025.
For those who assess interest rates and corporate demand, the industry mix in July raises a more detailed question: Does the growth come from sustainable private demand, or is it driven by temporary factors such as weather and a few construction projects? Construction expansion can boost engineering services, but it may not immediately improve the actual purchasing power of ordinary households; an increase in electricity consumption can raise the value added for that month, but it could also just be a short-term effect of heatwaves. If manufacturing and retail remain weak for several months in a row, companies may adjust their inventory and staffing plans accordingly; however, at present, this is just a risk scenario that needs to be monitored, and it cannot yet be assumed to have led to a chain reaction of decline.
Therefore, the most prudent judgment for July is that "the total volume remains unchanged while there is a differentiation in structure." The positive contributions from construction and electricity are real, as are the negative impacts from manufacturing and retail. If construction continues to grow and manufacturing and consumption stop declining, a monthly zero growth might just be a temporary pause; however, if commodity and retail sales continue to decline after the support from weather conditions fades, the economic momentum will need to be re-evaluated. For those who pay attention to Canada's macroeconomic trends, a single 0.0% growth rate is not a conclusion, but rather a signpost indicating that it is necessary to continue to examine industry-specific details.