

Wall Street is moving towards a market that will hardly ever close completely. Tokenized stocks are bringing stocks onto the blockchain, enabling continuous trading and settlement; at the same time, traditional brokers are also extending trading hours beyond regular trading times. In 2026, tokenized stock activity significantly accelerated, with billions of dollars in assets already represented and traded on the blockchain. With the increase in weekend and after-hours trading, tokenized stocks are beginning to test how continuous trading will reshape liquidity, settlement, and the way global investors access U.S. stocks.
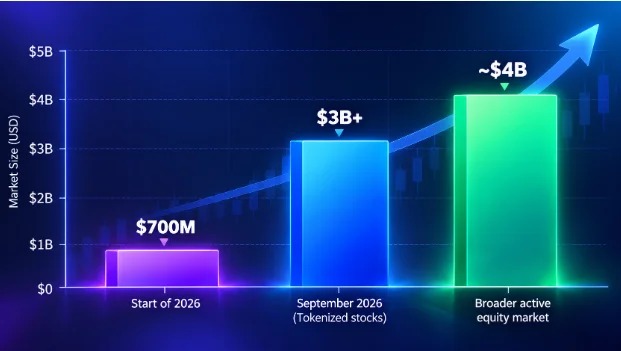
Tokenized stocks have surpassed $3 billion.
Tokenized stocks reached approximately $3 billion in September, becoming one of the fastest-growing areas in the tokenization of real-world assets. A broader dataset tracking active tokenized stocks indicates a market size of nearly $4 billion, which reflects differences in asset coverage and statistical methods. Today, over 1 million holders hold tokenized stock exposures in the blockchain market.
Trading volume is growing at a faster rate than asset size.
As the scale of underlying assets expands, trading activities for tokenized stocks are also rapidly increasing. Monthly trading volume rose from $237 million in January to $965 million in February, and then reached $7.9 billion in August. The turnover rate in August was 2.14 times, and it had reached 3.32 times in July, indicating a clear acceleration in trading activity relative to the base of active markets.
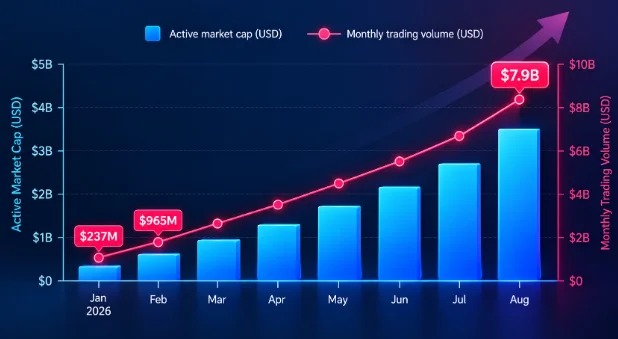
These data indicate that the rate of expansion of market trading activities is much faster than the base size of unliquidated tokenized stocks.
Tens of billions of dollars in tokenized stocks have been transferred between wallets.
In 2026, on-chain transfer activities have significantly expanded. The amount of tokenized stock transfers in the third quarter was approximately 100 billion US dollars, compared to about 6 billion US dollars in the first quarter. The volume of transfers includes movements between wallets and should not be equated with the volume of executed transactions.
This growth indicates that the volume of tokenized stock transactions between blockchain addresses and financial institutions has far exceeded the levels at the beginning of the year.
In September, tokenized stocks accounted for an average of 11% of DEX trading activity, while the average proportion for memecoin was 17%.
Another set of 30-day data estimates the trading volume of the tokenized stock DEX at approximately $20.9 billion, of which Uniswap V3 and V4 together account for about 60%. Stock exposures are increasingly being traded through the infrastructure originally built for crypto-native assets.
Weekend trading is creating new opportunities in the stock market.
Robinhood announced on September 29 that it plans to introduce 24/7 weekend trading for certain US stocks and ETF after regulatory approval is obtained. Its existing 24 Hour Market already provides trading services for some securities from Sunday evening to Friday evening.
The tokenized stock trading platforms are already in continuous operation. Once these two are combined, company news released on weekends can be reflected in prices before the traditional Monday trading session begins.
24/7 trading still depends on liquidity.
The market can remain open continuously, but that does not mean it can maintain the same level of depth throughout the day. When U.S. exchanges close, the flow of orders from traditional institutions and arbitrage channels decreases, making tokenized trading venues more dependent on specialized market makers and liquidity pools.
DeFi is converting stock tokens into financial assets.
In the tracked dataset, the total locked-up volume of the tokenized stock DeFi (TVL) increased from 21.6 million US dollars at the beginning of 2026 to 289.1 million US dollars on September 9th. The proportion of DeFi TVL in the market value of active tokenized stocks also rose from 2.2% to 7.2%.
Its use is no longer limited to holding and trading. Tokenized stocks can also serve as liquid assets and collateral in blockchain financial applications.
The distribution is concentrated on a few platforms only.
Therefore, market activities are not evenly distributed among the various issuers. Platforms with a mature user base can directly incorporate tokenized securities into their existing trading processes.
Tokenizing stocks doesn't always mean directly holding the stocks.
Tokenized stocks can adopt different legal and custody arrangements. Such tokens may represent rights to underlying securities, interests held through a custodian, or economic exposures formed through other structures.
For example, the stock token Robinhood is described as a tokenized debt security that provides an economic exposure, rather than legal or beneficial ownership of the underlying stock.
The regulatory framework introduced by the United States in September also set conditions for qualified tokenized securities trading venues, including requirements related to investor rights and market control.
Wall Street is extending trading hours along with the blockchain market.
The trend towards continuous stock trading is no longer limited to blockchain-native companies. Robinhood is preparing to offer weekend trading for some US stocks and ETF. Nasdaq has been developing an all-weather market model to extend trading hours on weekdays; NYSE and Blockchain.com are exploring the tokenization of US-listed stocks and ETF, as well as longer trading hours.
These two systems are moving forward from different starting points towards a longer market availability period.
Settlement may represent an even greater change.
The trading period is merely the most straightforward aspect of tokenization; settlement represents a more profound change in the underlying infrastructure. Tokenized assets enable the recording of ownership, transfer instructions, and settlement logic on the blockchain, thereby connecting the markets for securities, lending, and collateral.
Institutional products are already moving in this direction. BlackRock has launched a tokenized portfolio, allowing eligible non-U.S. investors to trade and transfer it around the clock, as well as use it as collateral for loans.
What will happen next?
Tokenized stocks are no longer just an experiment of putting stocks onto the blockchain. Today, this market boasts a capital base of several billion dollars, rapidly expanding trading activities, quarterly on-chain transfers exceeding 100 billion dollars, a growing level of participation, and a DEX that is still taking shape. The next challenge is to make these activities more profound and reliable, while also ensuring compatibility with the legal and market infrastructure that manages traditional securities.
The 24/7 model also exposes a type of structural trade-off. Continuous availability can expand access and create new opportunities for price discovery, but execution still depends on liquidity, market depth, reliable pricing, and clearly defined ownership. The usefulness of a token that is traded around the clock depends on the infrastructure that supports its trading, settlement, and custody.
This means that the next phase of tokenized stocks is not just about moving more stocks onto the blockchain. A bigger question is whether these assets can remain continuously connected to exchanges, brokers, custodian institutions, lending markets, and DeFi platforms without causing fragmentation of liquidity or weakening investor protection. If these components can be integrated, tokenized stocks could become part of a broader market structure, rather than just another form of traditional stocks.