

Preliminary data released by Germany's Federal Statistical Office on October 8th show that, after adjusting for seasonal and calendar factors, Germany's goods exports in August amounted to 137.6 billion euros, a decrease of 0.8% from July; imports amounted to 118.1 billion euros, showing a month-on-month increase of 0.9%. The corresponding trade surplus was 19.5 billion euros, lower than the 21.6 billion euros in July. The key point of these figures is not that Germany has suddenly lost its export capacity, but rather that external demand, imports, and the trade balance moved in different directions within the same month. For an economy that is highly dependent on manufacturing and cross-border supply chains, this divergence is more noteworthy than a single headline about "declining exports."
Year-on-year growth, why still can't it conceal the decline of that month?
On a year-on-year basis, in August, adjusted exports increased by 6.2% compared to the same month of 2025, while imports increased by 5.5%. This indicates that the same announcement can simultaneously show both "year-on-year growth" and "month-on-month decline," which are not contradictory to each other: year-on-year data compares the current situation to that of a year ago, while month-on-month data is closer to recent trends. To assess short-term momentum, it is preferable to look at month-on-month figures after adjusting for seasonal and calendar factors; to describe changes over a year, the corresponding year-on-year figures should be used. Directly subtracting unadjusted raw values from adjusted sequences will create meaningless disparities.
The Bureau of Statistics specifically notes that these results are still preliminary monthly foreign trade statistics, and the detailed structure has not yet been fully completed. Therefore, it is not possible to assert the specific reasons for overall trade changes or changes in any particular market based on these data. For example, a decline in exports to the U.S. market in a given month does not automatically prove that a certain policy, a type of vehicle, or a particular company is the sole cause. Price changes, delivery schedules, large orders, and statistical revisions can all affect monthly data. News reports may list possible directions for observation, but they should not present speculations as explanations that have already been confirmed by the statistical authorities.
Regional data makes this decline more specific. Germany exported 77.5 billion euros to EU member states, a decrease of 0.6% month-on-month; it exported 60 billion euros to countries outside the EU, a decrease of 1.1%. Among these, exports to the United States amounted to 13.5 billion euros, which is 6.3% less than in July, but still 22.6% higher compared to August 2025. The same market experiencing a monthly decline while showing annual growth serves as a reminder that a single percentage should not represent the entire trend. The UK market, on the other hand, saw an increase, with exports to the UK amounting to 7.9 billion euros, a month-on-month increase of 16.7%. The directions of different markets are not consistent, and Germany's exports are not facing a homogeneous impact.
The import side cannot be ignored either. Imports from sources outside the European Union increased by 2.2% month-on-month, while imports from EU sources decreased by 0.4%; however, total imports still rose by 0.9%. An increase in imports may indicate domestic demand, companies replenishing their stockpiles, or changes in the procurement of inputs. It could also be influenced by prices and transportation arrangements; therefore, it is not advisable to conclude that domestic demand has significantly strengthened based solely on the total amount. If companies increase their procurement of intermediate goods, future production may not grow accordingly. If energy or raw material prices rise, the change in nominal amounts may exceed the actual change in quantity. To determine the economic implications, further breakdown of commodities and subsequent manufacturing data are needed.
A narrowing trade surplus cannot be simply categorized as either good or bad.
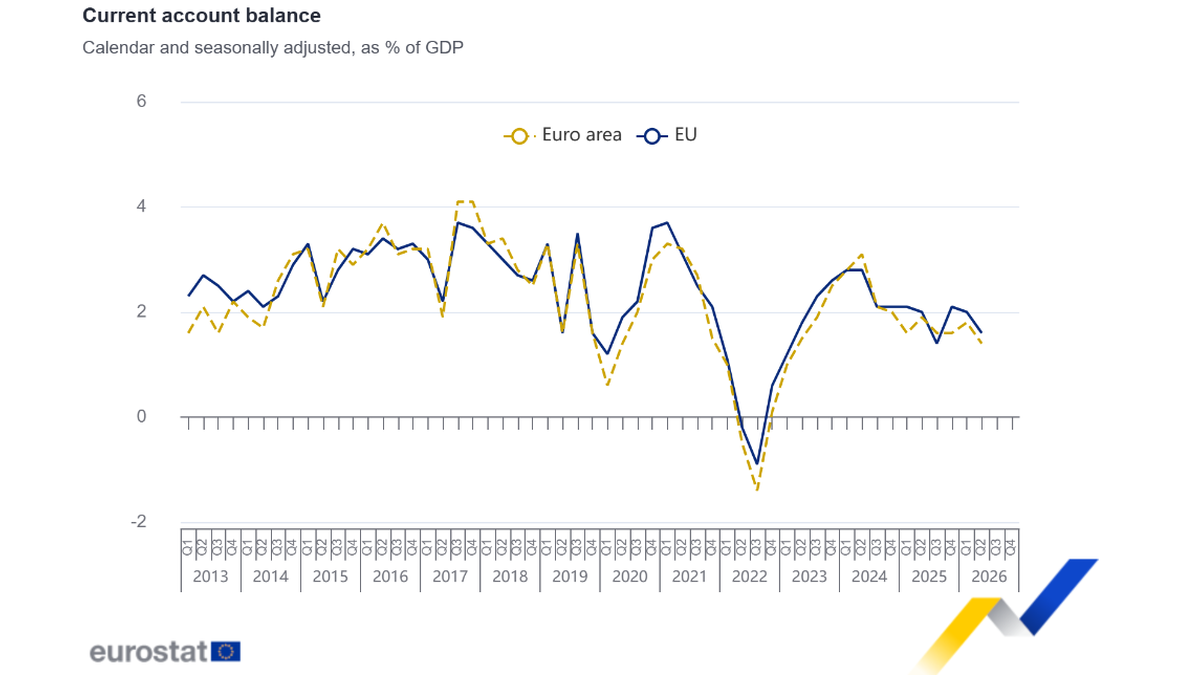
The trade surplus decreased from 21.6 billion euros in July to 19.5 billion euros in August, a result of the combined effects of exports and imports. A larger or smaller surplus is not simply a matter of better or worse; it reflects the relationship between a country's savings, investment, consumption, and external demand. If the decline in the surplus is due to companies purchasing equipment and expanding production, its implications may be quite different from a weak export situation while imports remain high. The current monthly data only tells us that the gap has narrowed; it does not provide a complete economic story behind it.
From the perspective of business operations, there are three subsequent signals in this report that deserve attention. First, whether the orders from major export markets continue to change, especially whether the fluctuations in a single month persist into the next announcement. Second, whether the increase in imports corresponds to an investment in production materials or to factors related to consumer goods and prices. Third, whether industrial production, manufacturing orders, and corporate surveys indicate the same direction. Only if trade data corroborates these indicators can the trend judgment be more confident; if other indicators suggest the opposite, then seasonal adjustments, one-time orders, and revision factors should be considered.
The announcement from the German Federal Statistical Office also lists the raw figures: in August, exports amounted to 123.4 billion euros and imports to 108.4 billion euros, resulting in a trade surplus of 15 billion euros without seasonal or calendar adjustments. These figures do not conflict with the previously mentioned adjusted figures of 137.6 billion, 118.1 billion, and 19.5 billion euros; the difference lies in the method of calculation. For readers, it is most important to avoid comparing the two sets of figures in the same sentence and then drawing conclusions about seemingly astonishing changes. Rigorous financial reporting involves not only quoting official figures but also placing each figure within its own statistical context.
As of this release, the conclusions are quite clear: Germany's exports fell month-on-month in August, while imports rose month-on-month, resulting in a narrower trade surplus after adjustment compared to the previous month; year-on-year, both exports and imports still maintained growth. These data are preliminary results, and officials have not attributed the overall changes to a single cause. Next, we need to wait for more detailed information on goods and regions, as well as data from subsequent months. For companies operating in the European market or those concerned with global manufacturing, this is a warning sign, but it is not a final judgment on the growth for the entire year.