The commercialization narrative of large models is facing challenges at the data level. After tracking the payment data of over 70,000 American companies, a giant in the industry Ramp found that only 1% of these companies contributed to 80% of the commercial spending in OpenAI and Anthropic. Moreover, this highly concentrated demand is reaching its peak – while the usage volume continues to rise, the actual dollar spending growth has nearly stagnated, and the penetration rate of paying users has also leveled off.
Ramp Chief Economist Ara Kharazian pointed out in his October AI index report that spending saw "almost zero growth" for two consecutive months in August and September. Although it managed to reach a new historical high at the beginning of October, it was only 1.5% higher than the peak in August. The core driving force behind the stagnation in spending is price deflation: prices continue to decline according to advanced models, and coupled with improved model efficiency, the average price per million Token is constantly falling, making the divergence between volume and price increasingly evident.
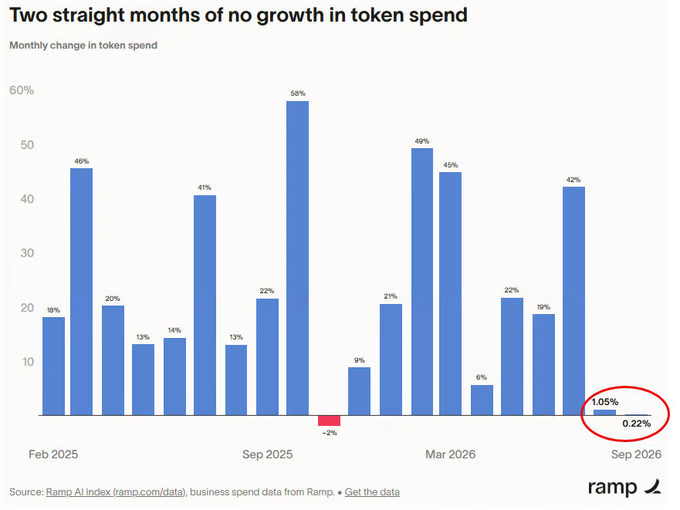
This signal has raised the alert of mainstream institutions. Goldman Sachs warns that the growth rate of demand for Token must outpace the decline in prices to support continued investment in computing power; Apollo's chief economist, Torsten Slok, citing data from Ramp, points out that the demand curve for computing power is "flat and highly sensitive to prices," meaning that corporate buyers will reduce their usage or switch to cheaper open-source alternatives at the slightest price fluctuation. Meanwhile, the founder of Citadel, Ken Griffin, has publicly stated that the market is "almost certainly" in a bubble.
High demand concentration; whale customers drive revenue
AI The degree of centralization of corporate expenditures is second to none among all software categories. Ramp Data shows that startups supported by venture capital have an average monthly expenditure of $76 per person, which is more than 10 times that of companies with private equity backgrounds.
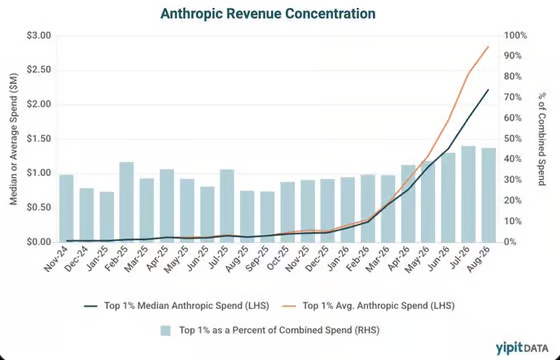
The concentration at the top is particularly prominent in Anthropic. According to YipitData, the top 1% of customers at Anthropic contributed 46% of the revenue in August, nearly doubling from 25% a year ago. The prospectus of Anthropic shows that just two unidentified customers contributed nearly a quarter of its revenue for 2025.
The flow of capital reveals the internal cycle of this ecosystem: Cursor's parent company, Anysphere, completed a $2.3 billion financing in November last year, with a valuation of $29.3 billion. The financing was co-led by Accel and Coatue, with Thrive Capital, Andreessen Horowitz, NVIDIA, and Google also participating. Three months later, Coatue jointly led a $30 billion Series G financing for Anthropic with a Singapore-based firm GIC; NVIDIA participated again in this round of financing.
Funds flow from Coatue to Cursor. Cursor converts this into Claude Token for consumption. The consumption is recorded as revenue in Anthropic. In turn, the revenue from Anthropic supports the valuation premium of the Anthropic shares held by Coatue.
Price war intensifies, Anthropic actual Token price cuts in half
Model prices are collapsing rapidly. The Ornn Anthropic Token price index – which measures the actual cost paid by customers per Token – has dropped from over $1.70 in mid-September to $0.83, setting a new historical low since the benchmark was introduced in June.
Even so, Anthropic is still more valuable than OpenAI. The index corresponding to OpenAI is currently at $0.45. The actual pricing of OpenAI plummeted at the end of July – at that time, it lowered the prices of GPT-5.6, Luna, and Terra models by up to 80%. This occurred just three days after the Chinese large-model company Moonshot released the open-source weights of Kimi K3, which is considered to have been the trigger for the chip stocks to enter a bear market that month. Since then, there has been a tendency to push the release of IPO until 2027.
The "Jevons Paradox" failed to materialize
A drop in prices stimulates a surge in demand, which ultimately leads to an increase in total revenue—this is the "Jevons' Paradox" logic commonly cited by AI bulls. However, the existing data does not support this conclusion.
In a report dated September 25, Goldman Sachs pointed out that based on data from Anera and OpenRouter, total demand for Token has increased by approximately 18 times since December last year. However, the growth rate of demand for high-gross-margin models is only half of the overall growth. The profit compression resulting from declining prices has been transmitted to the data center investment sector. Goldman Sachs estimates that the realized return on invested capital (ROIC) for five companies: Amazon, Alphabet, Meta, Microsoft, and Oracle, has dropped from 40% to 25%, representing the lowest level since 2016.
Torsten Slok is straightforward about this: 'The premise assumption of Silicon Valley is that there is an unlimited demand for computing power, but the recent slowdown in the growth rate of Token expenditures indicates that this demand may only exist when computing power is almost free.'
He warns that the key variable determining whether a data center construction model is viable is neither physical capacity nor power supply, but rather "the price that users are actually willing to pay for computing power." This price is supported by whether companies can convert the consumption of Token into revenue growth, improved profits, or substantial cost savings. "At present, these benefits have not yet been evident on a large scale. In the future, they may appear, or they may not."
Paid penetration is approaching saturation; growth will rely on depth rather than breadth.
Apart from the slowdown in head expenses, the expansion of the paid user base has also hit a bottleneck. Data from Ramp shows that in September, the adoption rate of AI payments within corporate networks only increased by 0.62 percentage points, to 55.9%.
Kharazian wrote in the report: 'It feels like we are already at the peak of the S-curve, and market growth will have to rely on more in-depth usage rather than just more paying users.'
This stands in sharp contrast to the statement made by Ramp Product Director Adam Sommer in June of this year – who stated at a forum in New York that “the largest AI spending enterprises on our Ramp platform have seen their monthly expenditures double over the past few months.” Three months later, the average expenditure of the top 1% of enterprises has fallen below the peak level of July.