Post-market trading on Wednesday once again demonstrated that exceeding expectations in performance is not always sufficient to satisfy investors, while promising expansion plans may drive a significant increase in stock prices. Lam Research ( NASDAQ : LRCX ) The stock price fell by nearly 7%, despite its quarterly performance exceeding expectations; QuantumScape ( NASDAQ : QS ) however, rose by about 12% after releasing positive updates regarding its battery technology and manufacturing plans.
However, despite the enthusiastic market response to QuantumScape, Wall Street's longer-term expectations for these two companies indicate a clearly favored candidate, and that company happens to be the one whose current stock price is weakening.
Lam Research Performance exceeded expectations, but the outlook is disappointing
The core business of this semiconductor equipment manufacturer also achieved solid growth, with system revenue increasing by 62% to $5.73 billion, and customer support sales growing by 40% to $2.49 billion. Profitability also exceeded expectations: the adjusted gross margin reached 52.4%, higher than the market's forecast of 52.1%; the operating profit margin was 40.2%, also above the expected 39.7%.
However, the company's outlook for the December quarter is only slightly higher than Wall Street's expectations, which may disappoint investors who were hoping to see stronger guidance. Lam expects revenue of $8.6 billion, with a range of $400 million, slightly higher than analysts' estimate of $8.54 billion. Its adjusted earnings per share guidance is $2.33, with a range of $0.15, which is also very close to the market's expected $2.32.
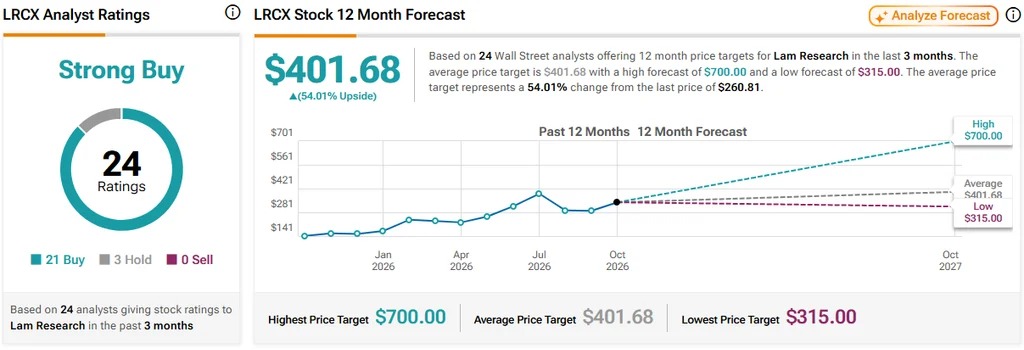
The selling pressure on Wednesday stands in sharp contrast to Wall Street's expectations for Lam over the next year. Analysts believe that the stock's trading price should be significantly higher than its current level, with a 12-month average target price of $401.68, which indicates a potential upside of about 54% from Wednesday's closing price. The bullish sentiment is not limited to a few optimists: among the 24 analysts covering LRCX, 21 recommend buying, while the remaining 3 suggest waiting and seeing, resulting in a unanimous rating of "strong buy" for this stock.
QuantumScape rises due to battery expansion plans and performance exceeding expectations
More importantly, QuantumScape has announced plans to establish a battery cell production line with a capacity of 100 megawatt-hours, targeting customers such as AI data centers, as well as potential clients in the aerospace and defense sectors. The company has already collaborated with German Muehlbauer Group to develop the necessary manufacturing equipment, and the battery cell production plan is set to begin in 2028.
This initiative is built upon the Eagle Line pilot factory located in San Jose, QuantumScape. The company is demonstrating its automated manufacturing capabilities for solid-state batteries there. Muehlbauer has already evaluated these processes and developed improvements aimed at supporting larger-scale operations.
QuantumScape has also been looking for business opportunities outside of electric vehicles, including energy storage applications for AI infrastructure. Earlier this month, the company launched QS PowerBlock, which is a design for energy storage within AI data center racks. The company claims that compared to traditional alternatives, this product can provide significantly higher power density and longer operating times.
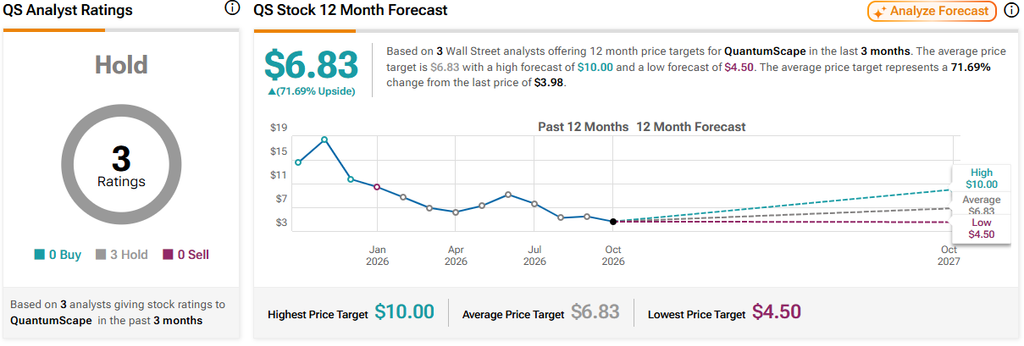
QuantumScape seems not to have yet caught the attention of the mainstream on Wall Street; currently, only 3 analysts are covering this stock. However, none of them recommend buying it, so QS has received a unanimous rating of 'Hold (i.e., neutral)' based on three 'Hold' ratings. Interestingly, its 12-month average target price is $6.83, which indicates a potential upside of nearly 72%. This suggests that although analysts are reluctant to explicitly recommend this stock, they still believe there is considerable room for it to rise.
Disclaimer and Disclosure