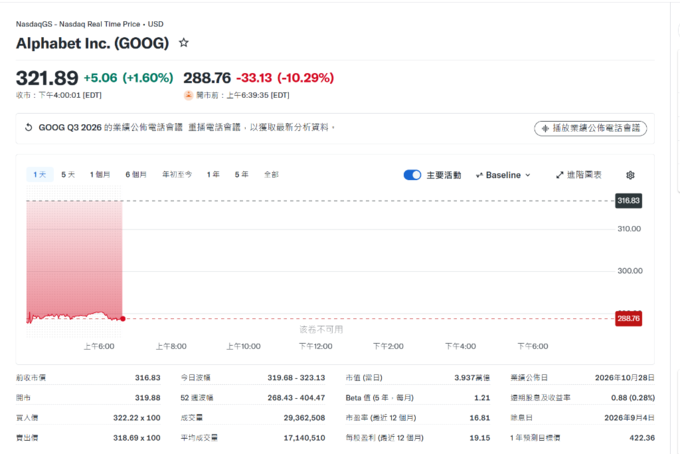
After the release of Alphabet's third-quarter financial report, major institutions on Wall Street immediately lowered their target prices. Search business revenue fell short of expectations, and coupled with unfavorable foreign exchange conditions and ongoing high capital expenditures, concerns about the company's free cash flow prospects have significantly increased.
According to Zuifeng Trading Desk, JPMorgan Chase has lowered the target price for Alphabet from $425 to $375. Goldman Sachs has also reduced its 12-month target price from $435 to $385, a decrease of about 11.5%, but has maintained its buy rating unchanged. Based on Goldman Sachs' closing price of $324.89 on October 28, the new target price represents approximately 18.5% upside potential.
Financial reports show that Alphabet's revenue from search and other services in the third quarter was 63.35 billion US dollars, lower than Goldman Sachs' forecast of 64.2 billion US dollars and the market's consensus forecast of 64.895 billion US dollars. At the same time, the company has maintained its guidance for capital expenditures in 2026 to be between 195 billion and 205 billion US dollars and has indicated that capital expenditures are expected to increase significantly in 2027, putting pressure on its free cash flow prospects, which has become one of the key concerns for investors.
Search revenue under pressure, with foreign exchange and comparative bases posing a dual drag
Alphabet In the third quarter, search and other business revenues increased by 12% year-on-year, which was lower than market expectations. Management attributed the main reason to unfavorable foreign exchange conditions, and also pointed out that the company is facing a challenging revenue comparison base. The acceleration in search revenue growth began in the third quarter of 2025, putting pressure on this quarter's year-on-year figures.
In addition, Goldman Sachs analysts also pointed out several specific factors in various vertical industries: retailers in some parts of the Asia-Pacific region were affected by the EU's abolition of the minimum tax exemption policy, while media and entertainment advertising spending saw a normalization decline after the 2026 World Cup. Management stated that the headwinds in foreign exchange in the fourth quarter are expected to be slightly greater than in the third quarter, and the pressure from comparative bases will also continue.
Looking at the overall performance for the entire quarter, Google's total revenue was $96.3 billion, which is lower than Goldman Sachs' estimate of $97.575 billion; YouTube advertising revenue was $11.207 billion, also falling short of expectations. GAAP earnings per share were $2.12, significantly lower than Goldman Sachs' forecast of $2.96 due to a loss of approximately $8.7 billion caused by fluctuations in the fair value of equity assets held by the company.
Strong cloud business, AI demand drives revenue beyond expectations
Cloud services became the biggest highlight of this quarter's financial report. According to Goldman Sachs data, Google Cloud's revenue in the third quarter reached $30.709 billion, a year-on-year increase of about 103%, exceeding Goldman Sachs' forecast of $29.556 billion by about 3.9% and the market's consensus forecast by about 5.7%. The operating margin expanded by about 1,250 basis points to 36.2% year-on-year.
Management disclosed that Google Cloud's backlogged orders have currently reached $561 billion, a year-on-year increase of 256%, of which approximately 55% is expected to be converted into revenue within the next 24 months. A Goldman Sachs report pointed out that there is strong demand from enterprises for AI; the sales of TPU systems have contributed significantly, with nearly 100 customers already using TPU. It is anticipated that this number will further increase in the fourth quarter and throughout 2027. Management also stated that insufficient supply of computing resources remains a key bottleneck restricting the further growth of the cloud business.
In terms of subscription services, management disclosed that the number of YouTube Premium subscription users has exceeded 150 million, with the overall growth rate of subscription revenue surpassing that of the advertising business. The demand for Google One AI packages also remains strong.
High capital expenditure and negative free cash flow have drawn attention.
Alphabet maintains a guidance range of $195 billion to $205 billion for capital expenditures in 2026, while Goldman Sachs' updated estimate is around $203 billion. For 2027, the company has not yet provided a specific guidance, but it has clearly stated that expenditures will "increase significantly," with Goldman Sachs anticipating them to be around $350.4 billion.
In this context, Goldman Sachs has further adjusted its forecast for free cash flow in 2027 to -$40.567 billion, with free cash flow in 2026 already turning negative (-$12.62 billion), representing a significant reversal from $73.26 billion in 2025. Depreciation and amortization expenses have also risen significantly, with Goldman Sachs estimating them at $38.774 billion in 2026 and expected to jump to $75.017 billion in 2027.
Management stated that they expect the return on capital ( ROIC ) to remain significantly higher than the cost of capital, but they acknowledge that the current discrepancy between free cash flow and large-scale investments will continue for a period until the computational constraints are alleviated.
Goldman Sachs lowers target price, maintains buy rating
Goldman Sachs has lowered its 12-month target price from $435 to $385, mainly reflecting a downward revision of forward earnings estimates and a slight contraction in the valuation multiple. In terms of valuation methodology, Goldman Sachs uses a 50/50 mix of EV / GAAP EBIT and the revised DCF ( EV / FCF-SBC ), with the EV / GAAP EBIT multiple being reduced from 26 to 24 to reflect the lower forward earnings estimates, while maintaining a growth ratio of approximately 0.80 times the multiple unchanged.
In terms of profit forecasts, Goldman Sachs has lowered its estimate for EPS in 2026 from $20.54 to $19.76, for EPS in 2027 from $15.50 to $15.01, and for EPS in 2028 from $19.15 to $18.53. Based on the current stock price, GOOGL is approximately 18 times Goldman Sachs' 2027 forecast for GAAP EPS (excluding net cash), and about 15 times for 2028.
Goldman Sachs analysts, led by Eric Sheridan, pointed out in their report that they remain optimistic about Alphabet's strategic positioning in the consumer and enterprise computing sectors over the long term. They believe that Alphabet combines the advantages of large-scale distribution capabilities (with a user base of over 1 billion) with substantial investments in computing power, representing a dual narrative logic that is currently undervalued by the market as AI monetization evolves from the "infrastructure layer" to the "platform layer" and "application layer." The main downside risks include: the search business being impacted by industry disruption, the long-term suppression of profit margins due to heavy asset investments, increasingly stringent regulatory scrutiny, and the impact of the macroeconomic environment on the valuation of growth stocks.