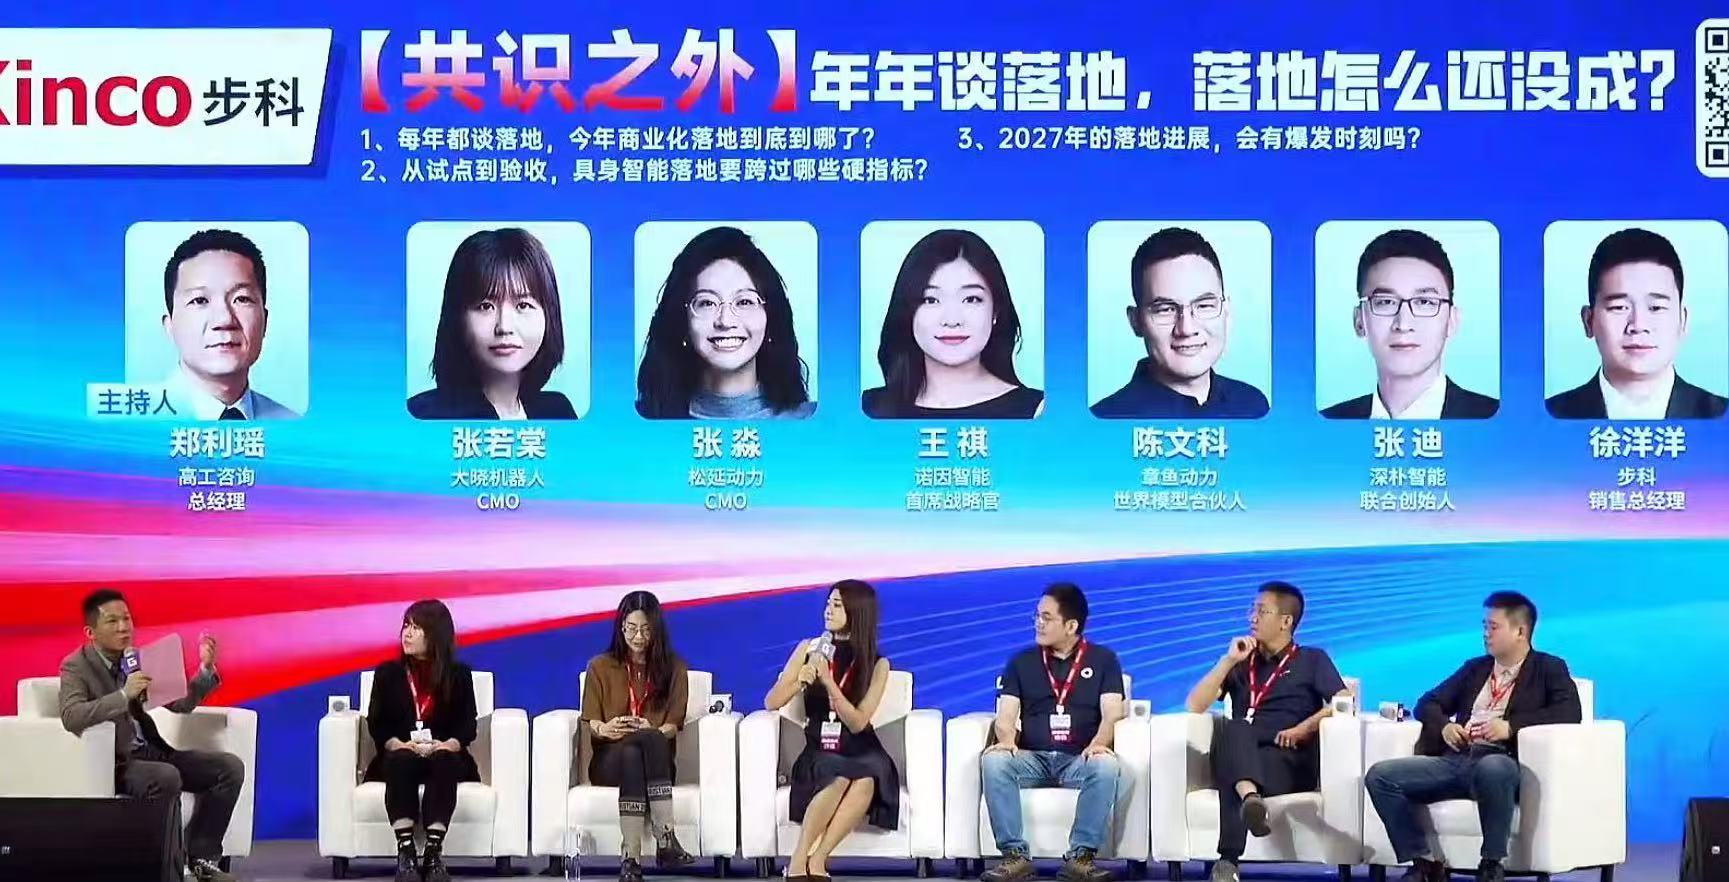
On November 3rd, a reporter from Yicai learned from the 2026 HighTech Humanoid Robot Annual Conference that data from HighTech Consulting indicates that the shipment volume of humanoid robots in China this year is expected to exceed 50,000 units, but the growth rate is lower than anticipated. With financing becoming cooler in the fourth quarter, it is predicted that more than 15% of humanoid robot companies will be eliminated over the next three years.
Gao Gong Consulting's General Manager, Zheng Liyao, stated that this year has seen a new level of commercialization for embodied intelligence, but the growth rate fell short of expectations. It is predicted that by 2026, the global shipment volume of humanoid robots will approach 60,000 units, with a market size of nearly $2 billion, representing a doubling of growth; among these, the shipment volume of humanoid robots in China will exceed 50,000 units, and the market size will surpass 10 billion yuan, also showing a doubling of growth. However, this year's shipment volume of humanoid robots in China will be lower than the initial forecast of over 60,000 units at the beginning of the year.
Zheng Liyao said that this is due to the fact that the implementation pace of humanoid robot products has been slower than expected. Looking at the new products, this year the humanoid robot industry in China has shifted from focusing solely on "manufacturing the body" to a dual approach of "body + model." However, the core issue remains unchanged; the industrial chain is still undergoing vertical integration, and most of the links are not yet perfected. Industrial applications are the main focus, and basic operations have become more widespread, but they have not yet been fully streamlined. Dexterous hand operations still require continued expansion of application scenarios.
In terms of financing, the enthusiasm for financing increased in the first three quarters of this year, but it cooled down starting from the fourth quarter. Data from GaoGong Consulting shows that in the first three quarters of 2026, the Chinese market saw 81.82 billion yuan in financing for humanoid robot bodies and 14.83 billion yuan in financing for other components such as dexterous hands.
"The humanoid robot market will continue to see price wars in 2027," predicts GaoGong Consulting. This year, the overall selling price of joint modules has decreased by about 30% year-on-year. It is expected that the price of small-sized humanoid robots under 1.2 meters will drop from 20,000 yuan this year to 18,000 yuan next year, those of medium-sized robots between 1.2 and 1.6 meters will fall from 115,000 yuan this year to 100,000 yuan, and those of large-sized robots over 1.6 meters will decrease from 268,000 yuan this year to 234,000 yuan. The focus of the industry is shifting towards delivery and deployment, with competition centered on practical applications in various scenarios.
Under the dual constraints of funding and commercialization, the humanoid robot sector is set to experience a significant round of consolidation in 2027. Zheng Liyao predicts that over the next three years, more than 15% of humanoid robot companies will go bankrupt or be acquired. Mid-tier companies will begin to focus their efforts, leading firms will amplify their advantages, and top-tier companies will strive to secure dominant positions within the ecosystem.
Going global will be the development trend. It is expected that the shipment volume of humanoid robots exported from China will also double by 2026. Zheng Liyao said that China's strength lies in its complete hardware supply chain, while overseas markets excel in large model capabilities and high-value applications. However, going global requires overcoming barriers such as product certification, safety compliance, data compliance, and localization services, and the transition from simply selling products to building an ecosystem.
"The humanoid robot industry is moving from prototype demonstrations to engineering-based deliveries, and from a general-purpose paradigm to targeted implementation in specific scenarios," believes Zheng Liyao. Currently, there are still challenges in commercialization, such as fragmented demand and a lack of 'killer' applications. In terms of industrialization, it is necessary to overcome issues like the disconnect between software and hardware, as well as inconsistent interfaces. As a result, capital has become more rational, and there is a trend towards 'deflating bubbles' (reducing excessive speculation).