

The U.S. stock market is experiencing a rare “two-sided market”: the S&P 500 index is less than 2% away from its historical high, but beneath the surface, almost all sectors sensitive to interest rates have been severely hit. The yield on 10-year U.S. Treasury bonds has risen to 5.34%, a new high since 2002, and this is quietly undermining those stocks that failed to capitalize on the narrative surrounding artificial intelligence.
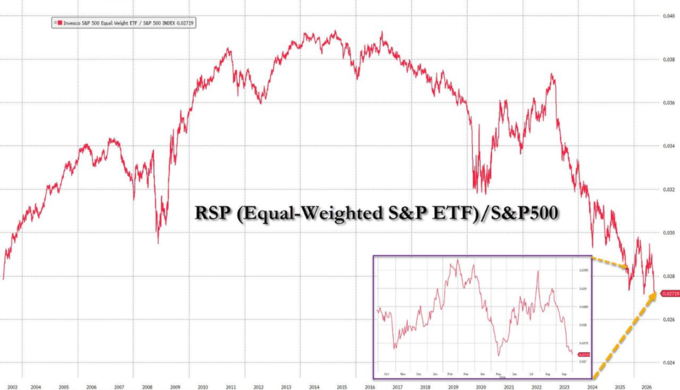
This apparent calmness is highly deceptive. Over the past month, the median stock price of the S&P 500 components has fallen by 5%, yet the index itself has remained virtually unchanged—the only support comes from the approximately 6% increase in the semiconductor sector over the same period. Meanwhile, the ratio of the equal-weight S&P 500 ( ETF ) to the S&P 500 index has just hit a record low. The equal-weight S&P 500 index has been declining for the seventh consecutive week, a situation that has only occurred twice before: during the bursting of the internet bubble in 2002 and during the bear market in 2022.
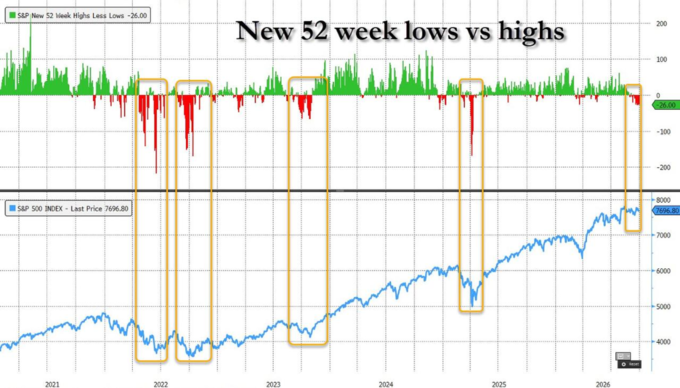
What is more concerning is that over the past 18 trading days, on 17 of them, the number of S&P 500 components hitting 52-week lows exceeded the number hitting new highs, a phenomenon that has persisted for 12 consecutive days. According to Bloomberg data, in previous instances of this situation, U.S. stocks were near their post-sale lows and then went on to rise; however, this time, the S&P 500 index remains near its historical highs.
iCapital Global Investment Strategist Dan Suzuki states:
"Most sectors of the market have fallen by at least 5% from their highs, with some sectors experiencing declines of over 15%. This is largely due to rising interest rates and the subsequent tightening of financial conditions."
Tech giants prop up the "hollow" index, with market breadth reaching historical extremes
The seemingly robust performance of the S&P 500 index relies almost entirely on the strong performances of a few major technology giants in the field of artificial intelligence. The equal-weight S&P 500 index, which assigns the same weight to each constituent stock, is facing its seventh consecutive week of decline. According to Bloomberg data, this has only occurred twice in history: after the bursting of the internet bubble in 2002, and during the bear market in 2022.
Tallbacken Capital Advisors CEO Michael Purves wrote in the research report:
"We don't see the current degree of market distortion as a reason to be bearish on the S&P 500; rather, we view it as a manifestation of a strong bull market, partly because significant technological disruptions are taking place."
His target price for the end of the year for the S&P 500 is 8,500 points, which represents a gain of about 11% compared to the current level.
However, this optimistic assessment is based on the premise that the AI narrative continues to be fulfilled. The Wealth Alliance President and Managing Director Eric Diton stated:
"The stock market can currently withstand higher yields – provided that economic and profit growth remain strong. However, the greatest risk to the stock market is problems arising in the construction process of AI. Once profit expectations are significantly lowered, it will trigger broader suffering in the stock market."
Small-cap stocks are approaching their callback range, with "zombie enterprises" accounting for over one-third
The rise in interest rates has a particularly direct impact on small-cap stocks. The Russell 2000 index just experienced its second worst quarter performance relative to the S&P 500 since 1999, underperforming by nearly 10 percentage points, and has fallen 8.5% from its historical high on August 14, approaching a technical correction zone.
According to Bloomberg data, among the constituents of the Russell 2000 index, so-called "zombie stocks" – companies that struggle or are unable to cover their debt interest with operating profits – account for more than one-third. These firms face significantly greater debt repayment pressures in a high-interest-rate environment than larger corporations, and if financing costs continue to rise, their viability will be further squeezed.
In the small-cap stock index, cyclical sectors such as finance and industry have a higher weight, and these sectors are under pressure in the current environment, which forms a sharp contrast with the structure dominated by technology stocks in the S&P 500.
Bank stocks have fallen into a correction zone, and the competitive threat from AI has increased the pressure.
Despite strong consumer spending and active corporate borrowing in the United States, bank stocks have not benefited. The NASDAQ Bank Index, which covers 24 large banks, has fallen more than 12% from its mid-August high, experiencing a technical pullback. Since the beginning of this year, the index has only gained 3.3%, far lagging behind the 12% increase of the S&P 500. KBW
In addition to interest rates and credit pressures, Muse AI Agent of Meta is also considered a new threat to financial stocks – this product may end consumers' "inertial behavior" of keeping funds in low-interest current accounts for long periods, thereby eroding banks' sources of low-cost funds.
Public utilities are approaching a bear market, and their "safe haven" status is being eroded by interest rates.
The utilities sector is one of the areas that has been most severely affected by this round of interest rate shocks. The S&P 500 utilities sector has fallen by approximately 17% since its February high, approaching a bear market range.
High yields fundamentally weaken the attractiveness of utility stocks: when short-term U.S. Treasury yields significantly exceed the dividend yields of utility stocks, the logic behind utility stocks being a "stable income alternative" no longer holds. In the third quarter, both electric power companies and the electric utility sub-sector fell by more than 10%, making them the largest losers within the sector. Only Constellation Energy and AES were the two companies that recorded positive returns.
At the same time, the sharp rise in interest rates has also increased the financing costs for the transition to renewable energy, further suppressing the long-term investment logic in this sector.
High-risk assets are in general retreat, and AI narrative becomes the last line of defense.
Even the most speculative corners of the market are not spared from pressure. According to Bloomberg data, a basket of technology companies tracked by Goldman Sachs – including Roku and Peloton Interactive among others – saw a 11% decline in the third quarter, marking the second worst third-quarter performance since records began in 2014.
According to data from Goldman Sachs and Bloomberg, companies with the most fragile balance sheets and the heaviest debt burdens only saw a 1.9% increase in the third quarter, which is the smallest quarterly gain since the Federal Reserve began this round of interest rate hikes at the beginning of 2022.
Wealth Consulting Group CEO Jimmy Lee stated that he is taking the opportunity of the declining valuations to buy into financial and industrial stocks, and believes that the surge in bond yields will not get out of control. However, he also warned:
The biggest risk for the S&P 500 is the accidental collapse of AI trading.
The vulnerability of the current market lies in the high concentration of the core logic that supports these indices. Once there are cracks in the profit expectations of AI, the widespread damage, which has been concealed by the aura of tech giants, will emerge in a more violent manner.