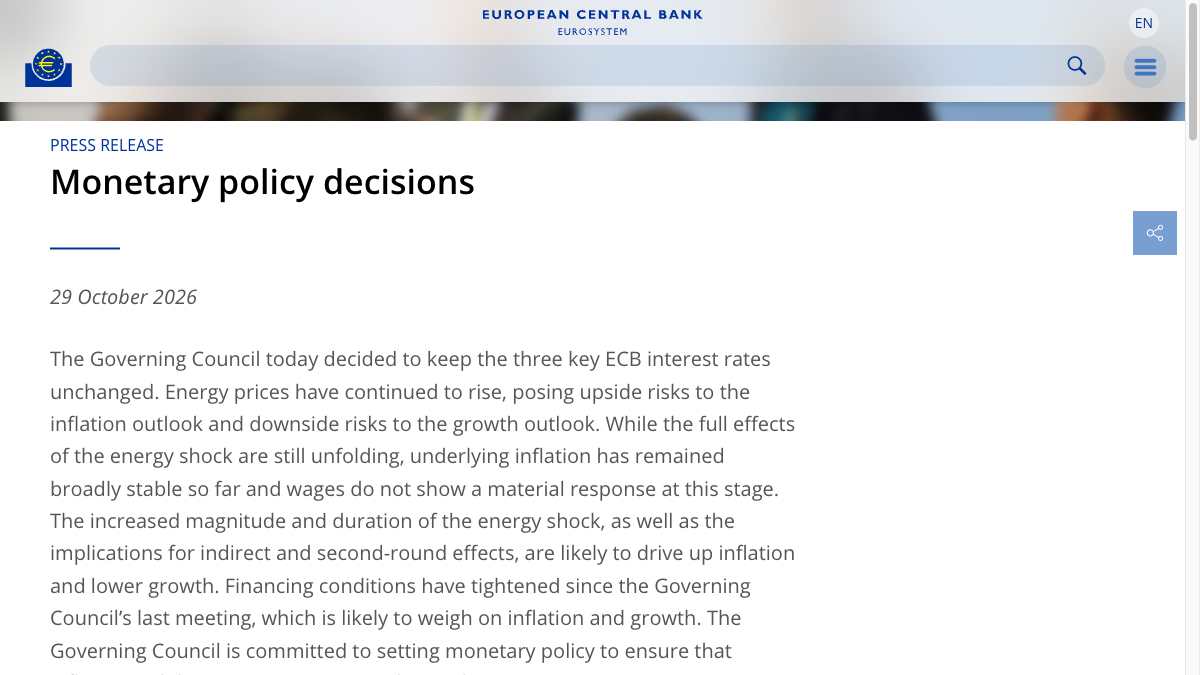


On October 29, the European Central Bank maintained the deposit facility rate at 2.50%, while the main refinancing rate and the marginal lending rate remained at 2.65% and 2.90% respectively. Although the numbers have not changed, the resolution states that since the last meeting, financing conditions have tightened, which may lead to lower inflation and growth. To assess the intensity of policy, one cannot simply focus on whether the interest rate buttons will be pressed again.
This resolution is faced with pressures in opposite directions. Energy prices continue to rise, posing upward risks to inflation and downward risks to growth. For businesses and households that bear the costs, the same energy shock not only increases their bills but also squeezes the space for other expenditures. What central banks need to determine is how these forces are transmitted, rather than simply choosing a direction for the overall inflation figure.
The announcement does not describe the impact of the shock as having already passed. It states that the full effects of the energy shock are still unfolding, that underlying inflation has remained largely stable so far, and that wages have not shown any substantial reaction at this stage. These statements define the time frame for observation: the lack of obvious reaction at present does not guarantee that wages and other prices will not adjust in the future.
Pause the action and retain the judgment for subsequent transmission.
The resolution also points out that the magnitude and duration of energy shocks, as well as the implications of indirect and secondary effects, may drive up inflation and reduce growth. Only by considering this alongside stable base inflation can we see that the current data and future risks are not the same thing. The current relative stability and the increasing pressures in the future can coexist.
Wages thus become a conditional piece of evidence. The announcement can only support the claim that 'there is no substantial reaction at this stage,' but it cannot support the assertion that 'wages have gotten out of control,' nor can it confirm that 'the impact has been completely absorbed.' For employers and borrowers, this distinction affects how they interpret the situation regarding interest rate maintenance: policymakers are observing the effects of these developments and have not provided a clear next step to follow.
Another aspect that is easily overlooked is the financing conditions themselves. Even if the interest rates of the three policies remain unchanged, officials still judge that the financing environment has tightened compared to the previous meeting. This statement changes the intuition that 'without an interest rate hike, there are no new restrictions.' However, the resolution does not list individual items such as loan interest rates, bond yields, or credit volumes, so it cannot be attributed entirely to a single market change.
The analysis that can be drawn from the text is that the impact on borrowing activities needs to take into account both policy interest rates and the actual financing environment. The former is a price explicitly determined by the central bank this time, while the latter is part of its assessment of how policies affect the economy. Combining the two into a single figure will overlook the transmission conditions that the decision itself emphasizes.
Interest rates remain unchanged, and the asset portfolio continues to shrink.
The resolution also maintains another ongoing action: the combination of the asset purchase program APP and the emergency purchase program for the pandemic PEPP is being scaled down at a measurable and predictable pace, and the eurozone no longer reinvests the principal of maturing securities. Interest rates remain unchanged, and the previous asset portfolio arrangements have not been halted.
For those who observe liquidity, this adds another layer to the policy landscape. New interest rate actions, whether the maturing principal will be reinvested, and the market financing environment are described separately for different aspects. This announcement does not provide an amount based on which to calculate the scale of balance sheet reduction for the month, therefore, it is not possible to derive a figure for capital withdrawal from the statement of 'continuing to shrink'.
In this set of statements, the mid-term goals also differ from the timing of the current shocks. The central bank has not promised that energy prices will immediately fall back, but rather places its policy choices within the process of inflation returning to target levels.
The European Central Bank continues to emphasize its medium-term inflation target of 2%, adopting a data-driven approach that is assessed at each meeting. The basis for this includes inflation prospects and risks, newly available economic and financial data, underlying inflation dynamics, as well as the effectiveness of monetary policy transmission. This is not a predetermined interest rate path, nor can it be interpreted as a guarantee of an interest rate hike or cut at the next meeting.
Announcement on the retention of the policy transmission protection tool TPI to address unfounded and disorderly market dynamics that pose a serious threat to policy transmission. The tool can be in different states of activation; this announcement does not introduce any new intervention measures. For borrowers in different regions, stable policy transmission is the goal expressed by the central bank, but it cannot replace the loan conditions they face individually.
This resolution does not provide the market with a clear next direction, but it clearly outlines the current constraints: energy pressures are still developing, the response of fundamentals and wages still needs to be discerned, financing conditions have become tighter, and asset portfolios continue to shrink. When companies make financing arrangements, they can rely on these existing conditions; however, treating "unchanged interest rates" as meaning that costs and risks remain unchanged will result in missing the most useful changes mentioned in the announcement.